The Seattle metro economy — King, Snohomish, and Pierce counties — produced $488 billion of real output in 2023, the most recent year the Bureau of Economic Analysis publishes for metro areas. That is up 6.2% from 2022, which the BEA ranked as the fastest growth of any U.S. metro with more than 1.5 million people (Houston was next, at 5.4%). Information and tech alone generated $133.7 billion of it.
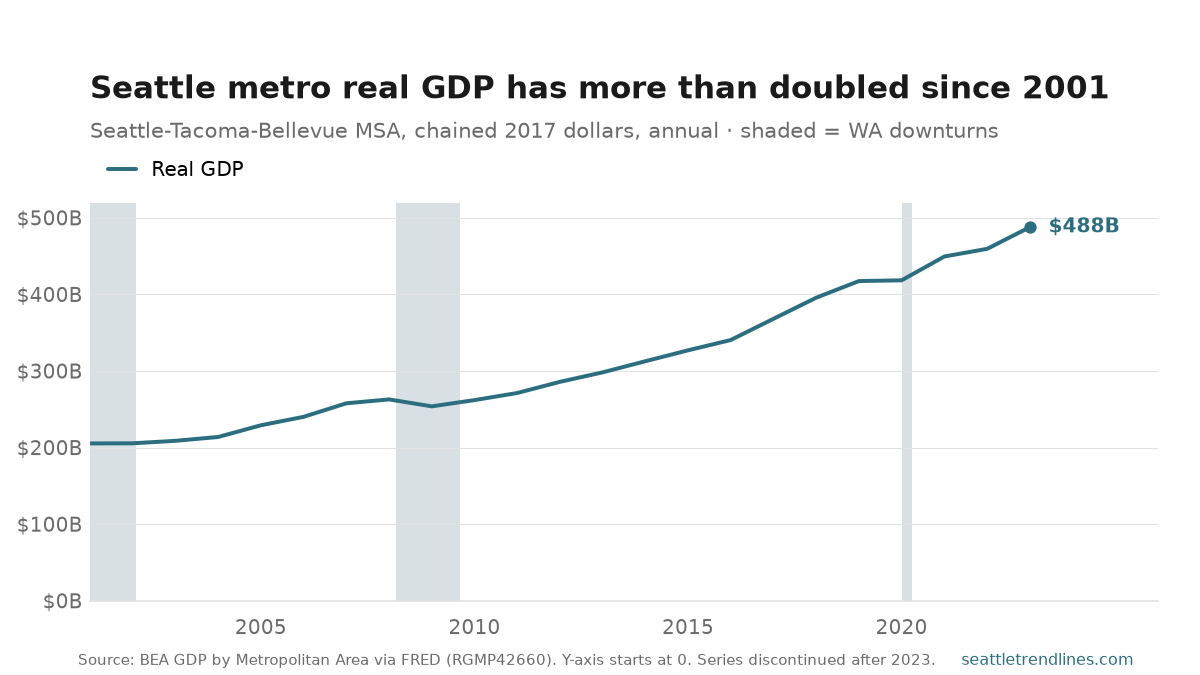
Real output has grown 2.4-fold since 2001, from $205 billion. The line bends upward after 2016: the cloud-and-Amazon stretch of 2017–2019 added real growth of 8.2%, 7.5%, and 5.5% in consecutive years, the strongest run in the series.
What stands out against the shaded bands is how little the contractions bit. The 2001 dot-com bust — which hit tech towns hard — left Seattle’s real GDP essentially flat (about +0.1% in both 2001 and 2002) rather than shrinking. The only outright annual decline in twenty-three years came in 2009, down 3.4% in the Great Recession, and it was erased by 2011.
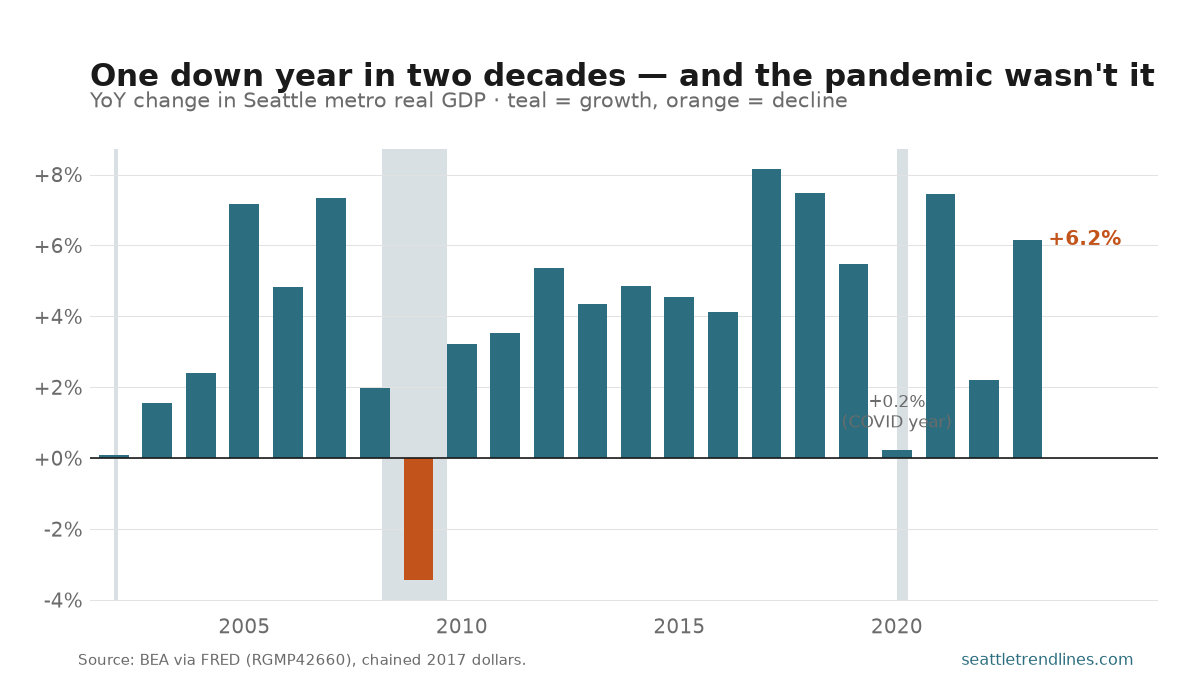
The pandemic is the real tell. Most metros’ output fell in 2020; U.S. real GDP dropped about 3.5% that year. Seattle’s rose 0.2% — flat, but on the right side of zero — because the things that power this economy (cloud services, software, e-commerce logistics) were precisely the things that boomed while people stayed home. Growth then resumed at 7.4% in 2021.
Two caveats. This is real GDP in chained 2017 dollars, so the doubling is genuine output growth, not inflation; in current dollars the 2023 figure is a larger-looking $566.7 billion. And 2023 is the end of the line: the BEA has discontinued its metropolitan-area GDP series, so there is no official 2024 or 2025 metro number to add — only the underlying county estimates, released on a lag.
Source: U.S. Bureau of Economic Analysis, GDP by Metropolitan Area (real GDP, all industries, chained 2017 dollars), accessed via FRED series RGMP42660 (real) and NGMP42660 (nominal). Geography: Seattle-Tacoma-Bellevue, WA MSA (CBSA 42660 = King, Snohomish, and Pierce counties). The “fastest among large metros” ranking and the $133.7B tech/information figure are from BEA’s December 4, 2024 release, as reported by Axios Seattle. State downturns: Philadelphia Fed Coincident Economic Activity Index for Washington via FRED. Annual; BEA released 2023 metro estimates in December 2024 and has since paused MSA-level publication.
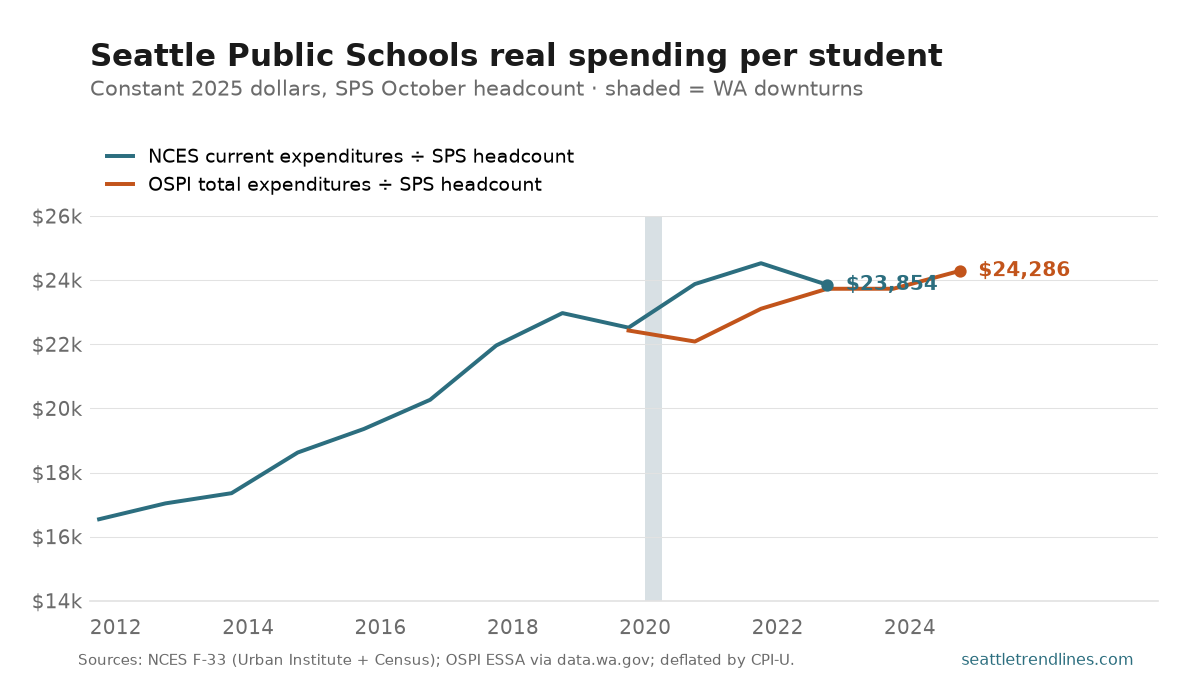
Measured against the district’s own October headcount, real spending per pupil climbed from about $16,500 in 2011–12 to $24,286 in 2024–25 (constant 2025 dollars) — roughly a 47% real increase, driven by the post-McCleary funding surge of the mid-2010s, with growth cooling since.
The shaded band is where the two independent sources overlap (2019–20 through 2022–23). At both ends of that window they agree almost exactly — within 0.4% in 2019–20 and 0.5% in 2022–23. In between, the federal NCES “current spending” line jumps 6–8% above the state’s ESSA-based line: that’s the wave of pandemic ESSER relief, which the NCES measure books in full while OSPI’s ESSA figure excludes part of it. By 2022–23, with relief winding down, the two reconverge. It’s a clean illustration that which spending definition you use matters most exactly when a one-time funding shock hits. (Y-axis starts at $14,000.)
The two measures, and why use both:
NCES current expenditures ÷ SPS headcount. Federal F-33 operating expenditures (Urban Institute through 2019–20, U.S. Census Bureau for 2020–21 to 2022–23), over SPS’s October count. Plus: a standardized, nationally comparable definition with a long back-run; the two F-33 sources match within 0.2% where they overlap. Minus: still released with a lag (ends 2022–23), and it fully books one-time federal surges like ESSER.
OSPI total expenditures ÷ SPS headcount. Washington’s ESSA expenditure total over the same headcount. Plus: state-official and current through 2024–25. Minus: ESSA accounting excludes some spending (so it understates the ESSER years), and it only begins in 2019–20.
Using SPS headcount as the common denominator (rather than NCES fall membership or OSPI’s annual-average FTE) raises the per-pupil figure by roughly 3% and is the most locally meaningful count — but it’s why this view starts in 2011–12, the first year of consistent district headcount.
Sources: NCES Common Core of Data district finance survey (F-33), current expenditures, via the Urban Institute (through 2019–20) and the U.S. Census Bureau School System Finances API (2020–21 to 2022–23); OSPI ESSA per-pupil expenditure (total expenditures, data.wa.gov, 2019–20 to 2024–25); both divided by SPS October headcount. Deflated by BLS CPI-U (annual average). Overlap agreement: 2019–20 +0.4%, 2022–23 +0.5%; pandemic years 2020–21 +8.1%, 2021–22 +6.1%. Annual; OSPI posts the new school year each winter (2025–26 expected early 2027).
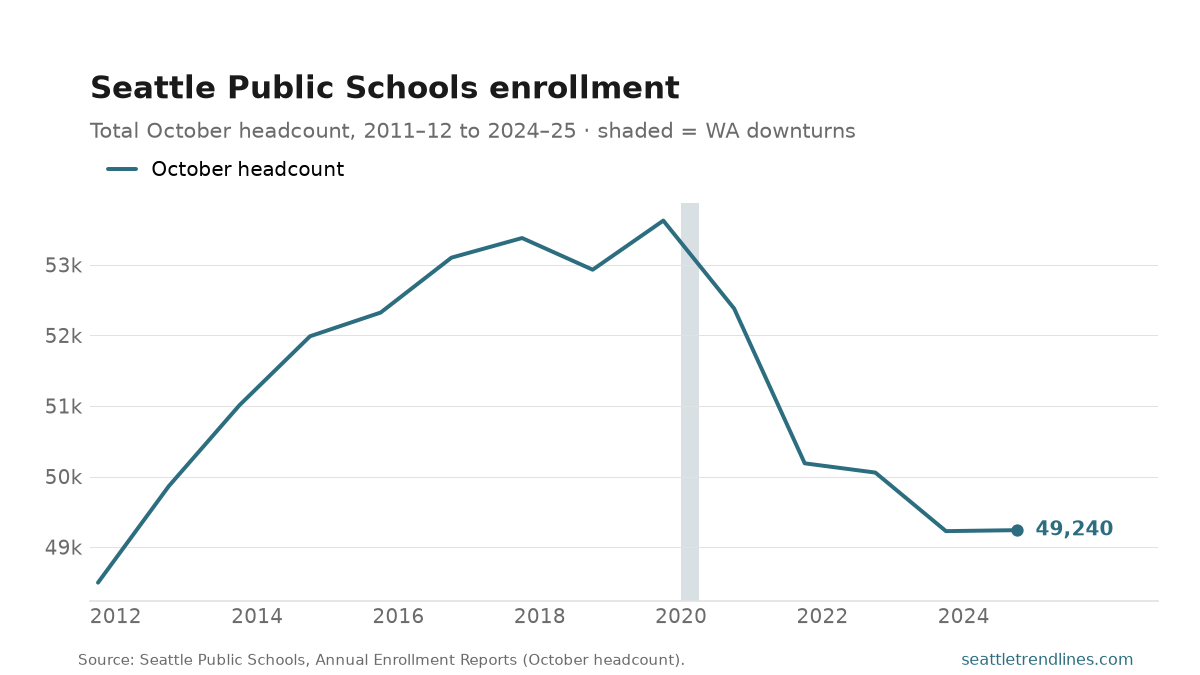
Enrollment peaked at 53,627 students in 2019–20, then fell sharply over the next two years. By 2024–25 the district counted 49,240 — down about 4,400 students, or 8%. It has roughly leveled off since 2022–23.
Source: Seattle Public Schools, Annual Enrollment Reports (October headcount). Annual; the 2025–26 count is expected in the next report, typically released the following spring/summer.
For four years the defining fact of the King County housing market was scarcity: inventory fell to a low of 746 active listings in January 2022, and bidding wars followed. That era is over. At the end of June 2026 there were 6,913 homes for sale — the highest count in the decade Realtor.com has tracked the county, the fourth straight month to set a series record, and 19% more than a year earlier.
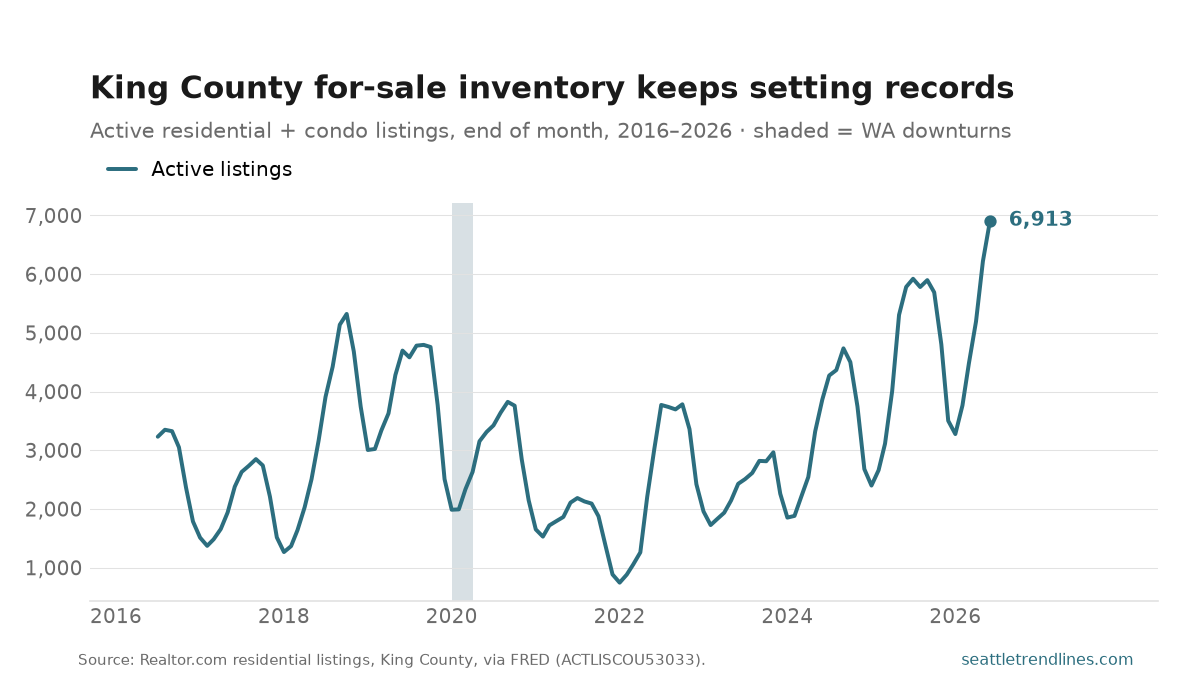
Inventory is seasonal — it builds through spring and summer, thins in winter — so the cleaner signal is the year-over-year climb, which has now run for several spring seasons. Supply is rebuilding faster than demand: the Northwest MLS put the county at roughly 3.4 months of inventory in May, still under the four- to-six months most consider balanced, but the loosest in years. The permit pipeline turning back up suggests more supply behind it.
Prices have not followed inventory down by much. The median list price was $850,000 in June 2026 — off 4% from a year earlier and about 10% below the $949,248 peak of May 2022, but still roughly 50% above where the series began in 2016.
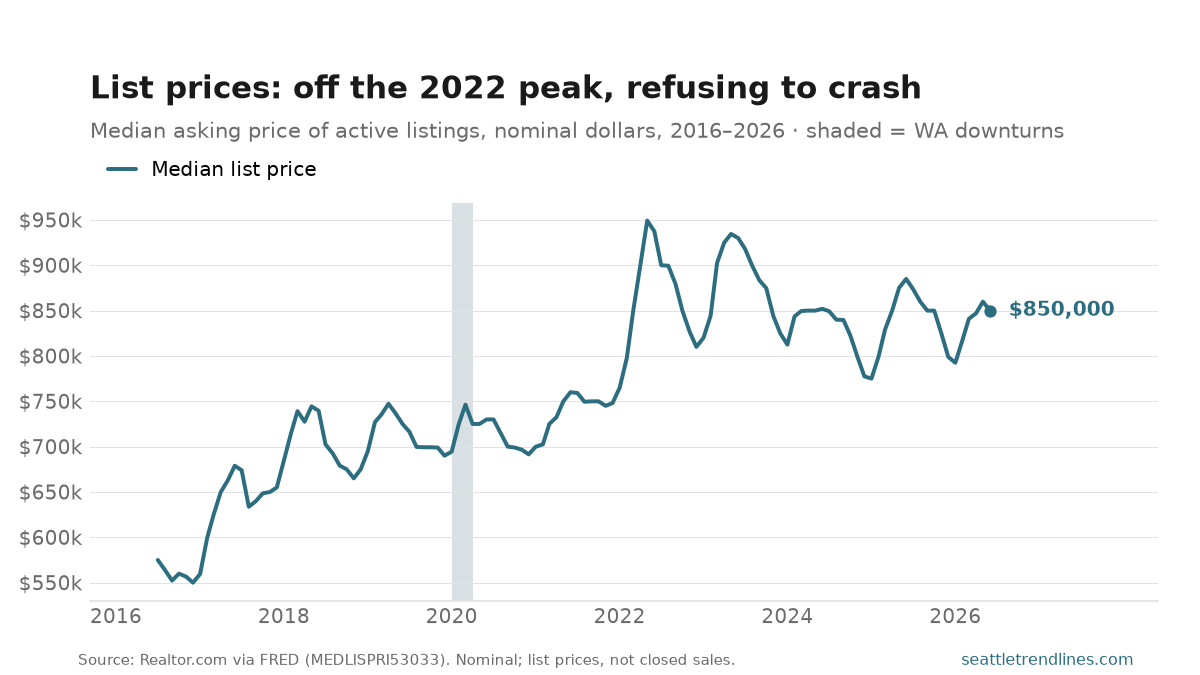
The market’s pace has settled rather than seized: the median listing sits 37 days before going under contract, about the same as a year ago and a week slower than two springs back. More homes, on the market a little longer, with prices drifting down — a buyer’s market by the standards of the last decade, even if it would not have looked like one in 1995.
Two caveats on the source. First, these are list prices from active listings, not closed-sale prices: for the actual transacted figure, the Northwest MLS reported a King County median sale price of $875,000 in May 2026 — close to the list-price line, and the number to cite when a local sale price is needed. We chart the Realtor.com/FRED listing series because it is clean, current, and free to republish with attribution; NWMLS’s own statistics carry terms that restrict derivative charts. Second, this chart is nominal — unlike the blog’s usual inflation-adjusted dollar charts — because list prices are the number buyers and sellers actually negotiate; in real terms the pullback from the 2022 peak is larger.
Source: Realtor.com Residential Listings for King County, WA (FIPS 53033), via FRED — active listings, median list price, median days on market. Closed-sale figures: Northwest MLS Monthly Market Snapshot (May 2026). State downturns: Philadelphia Fed Coincident Index for Washington. Monthly; FRED posts each month’s figures early the following month, and this chart refreshes on the next daily build.
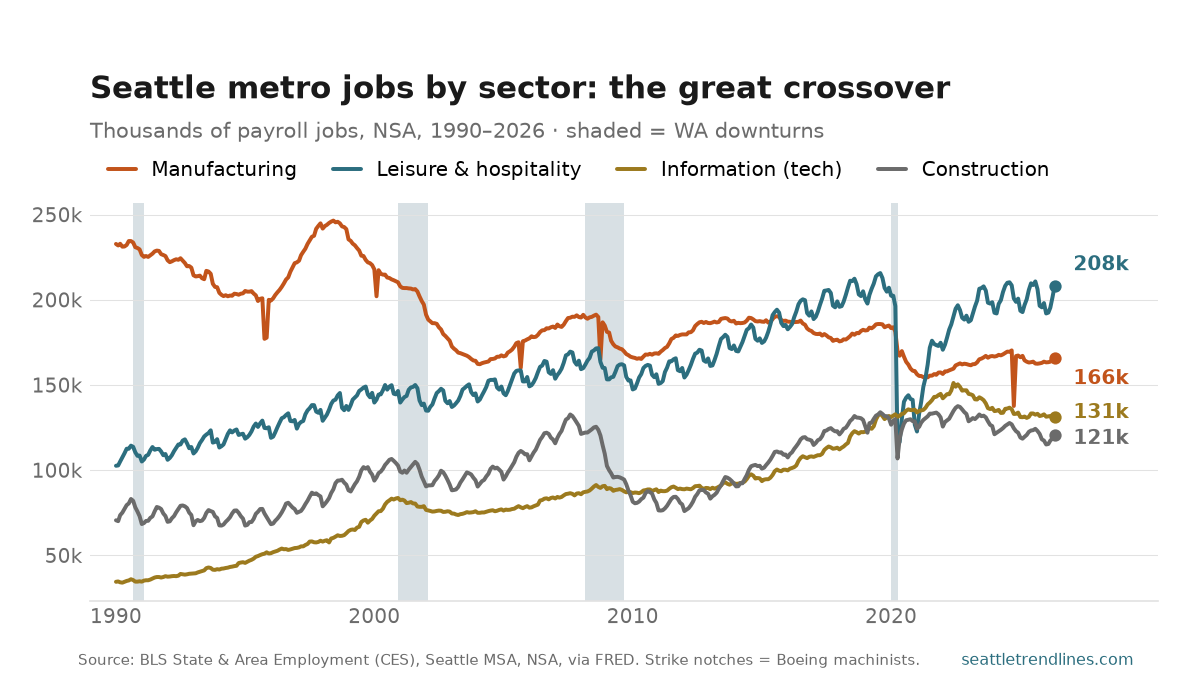
Thirty-six years ago, the Seattle metro economy was a manufacturing town: Boeing and its suppliers employed about 233,000 people in 1990, while the Information sector — software, publishing, telecom, the bucket that holds “tech” — was a rounding error at 34,500. Those two lines have spent a generation converging, and a third, leisure and hospitality, has quietly passed them both.
The story in one chart. Manufacturing (the Boeing cycle) has lost about a third of its 1990 workforce, sliding to 165,800 by May 2026; the violent single-month notches in 1995, 2005, 2008, and again in October 2024 are machinist strikes, visible because this series is not seasonally adjusted. Information climbed almost without interruption for thirty years — the Microsoft-then-Amazon ascent — peaking near 151,000 in mid-2022. It then fell for three consecutive years to the low 130s, off roughly 13% from that peak: the local fingerprint of the 2023–2025 tech retrenchment. Leisure and hospitality took the hardest pandemic hit of any sector, collapsing from about 202,000 to 114,400 in a single month in spring 2020, but it has not only recovered — at a record 208,200 it is now the largest of these four, having overtaken a diminished manufacturing sector around 2015. Construction remains the cyclical one, up from 71,000 in 1990 to 120,900 but well off its 2022 high as higher rates bit — the permit slump made flesh.
Year over year the picture matches the stalled total: payrolls were 2.14 million in May 2026, flat on the year. Manufacturing (+1.6%) and leisure (+1.2%) edged up, construction fell 1.3%, and information was essentially unchanged (−0.1%) — which, after three years of decline, is itself a kind of news: the tech slide has stopped, at least for now.
A note on the construction line: FRED discontinued the seasonally-adjusted Seattle-MSA construction series at the end of 2024, so this is the mining, logging, and construction supersector, not seasonally adjusted. In this metro, mining and logging are negligible, so the line reads as construction.
Source: U.S. Bureau of Labor Statistics, State & Area Employment (CES), Seattle–Tacoma–Bellevue MSA, not seasonally adjusted, via FRED — Information, Manufacturing, Mining/Logging/Construction, Leisure & Hospitality, Total nonfarm. State downturns: Philadelphia Fed Coincident Index for Washington. Monthly, about three weeks after month-end; this chart refreshes on the next daily build.
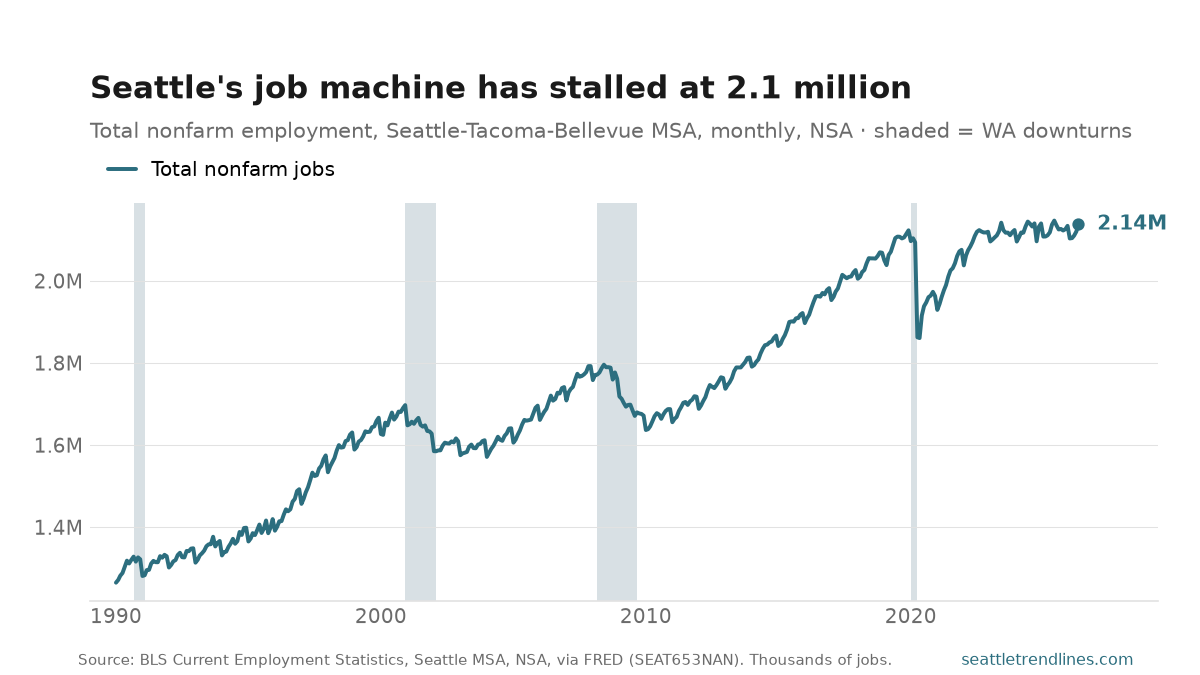
This is the region’s whole economic story on one line: 1.27 million jobs in 1990, 2.12 million now — the metro economy adding two-thirds again to its payrolls while the population grew to match. Every shock is legible. The dot-com flatline. The 2008–09 slide. The 2020 cliff — a quarter-million jobs gone in three months — followed by the fastest recovery on the chart. Even the October 2024 Boeing machinist strike shows up, a 44,000-job notch that snapped back the next month.
The right edge is the news, and the news is stillness. April’s count of 2,120,100 was up just 1,800 jobs — 0.1% — from a year earlier. Outside of recessions, this series simply doesn’t do that: year-over-year growth ran 2–3% through the 2010s and stayed positive even through the 2018–19 trade jitters. A flat year with unemployment still low reads as an economy at stall speed — not shedding workers, not hiring either. Whether that resolves into a downturn or a reacceleration is exactly what the next few months of this chart will show.
One reading note. The series is not seasonally adjusted, so the correct comparison is always to the same month a year ago — the annual sawtooth (summer peaks, January dips) is calendar, not economics. The NSA peak of 2,146,900 last June will likely be tested this summer; whether 2026 clears it is the cleanest single test of whether the stall is ending. For which industries are doing the stalling, see the jobs-by-sector breakdown.
Source: U.S. Bureau of Labor Statistics, State and Area Employment, Hours, and Earnings (CES), total nonfarm, Seattle-Tacoma-Bellevue WA MSA, not seasonally adjusted, via FRED series SEAT653NAN. Thousands of jobs, dated to the first of the month. New months post about three weeks after month-end; this chart refreshes on the next daily build.
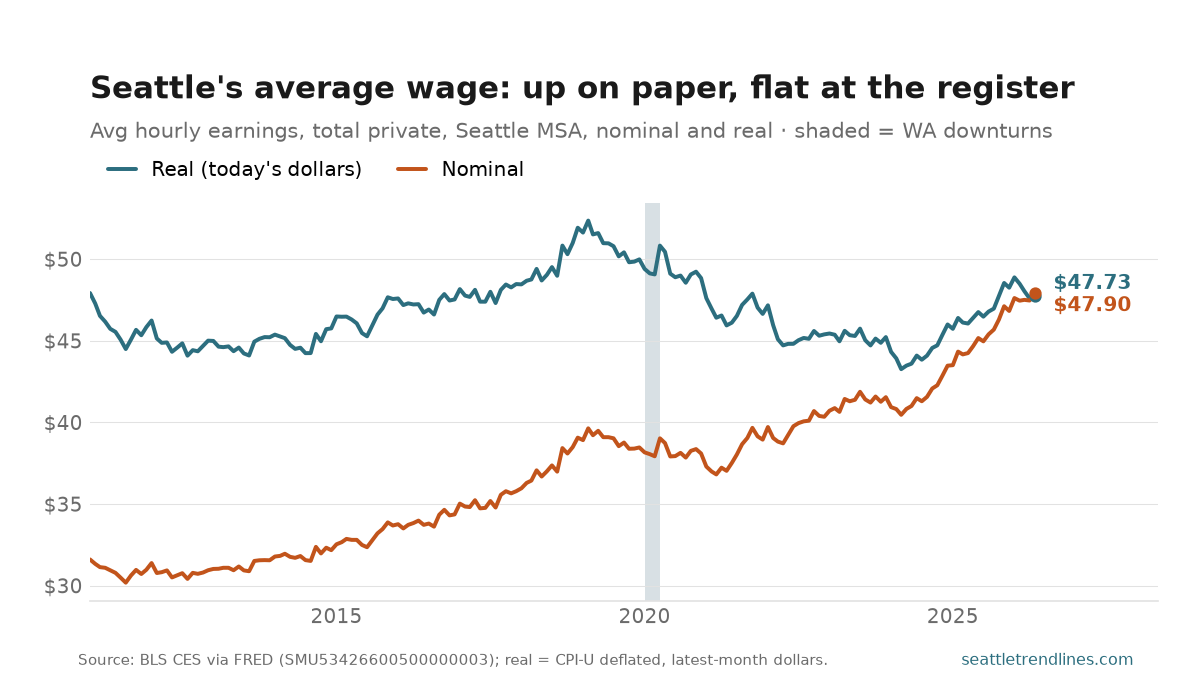
The average private-sector worker in the Seattle metro earned $47.70 an hour in May, up 6.8% from a year earlier — nominal wage growth that would have been front-page news any time in the 2010s. The teal line tells that story: pay up better than 50% since 2011, accelerating since late 2024.
The gray line tells the other one. Run the same series in today’s dollars and the average wage peaked in February 2019 at $52.55, was ground down 17% by the 2021–23 inflation to a trough of $43.42 in March 2024, and has since clawed back about 10%. Even after two years of unusually strong real gains — nominal growth near 7% against inflation near 4–5% — the average hour of work still buys about 9% less than it did in early 2019. That’s the whole inflation era in one picture: the raise arrived, and the register took it.
The caveats here are load-bearing, so read them. This is an average, not a median — it moves when the workforce changes shape, not just when anyone gets a raise. Some of the 2019 peak is exactly that: a tech-heavy boom pushing the mix upward, and some of the 2021 sag is low-wage hiring coming back. It’s also not seasonally adjusted and covers only private employees, and the series only begins in 2011. Direction and rough magnitude are trustworthy; any single month, less so. Pair it with the unemployment rate to see whether pay gains are coming from a tight labor market or a shrinking one.
Source: U.S. Bureau of Labor Statistics, State and Area Employment, Hours, and Earnings (CES), average hourly earnings of all employees, total private, Seattle-Tacoma-Bellevue WA MSA, not seasonally adjusted, via FRED series SMU53426600500000003. Real line deflated by U.S. CPI-U (CPIAUCNS) to the latest month. New months post about three weeks after month-end; this chart refreshes on the next daily build.
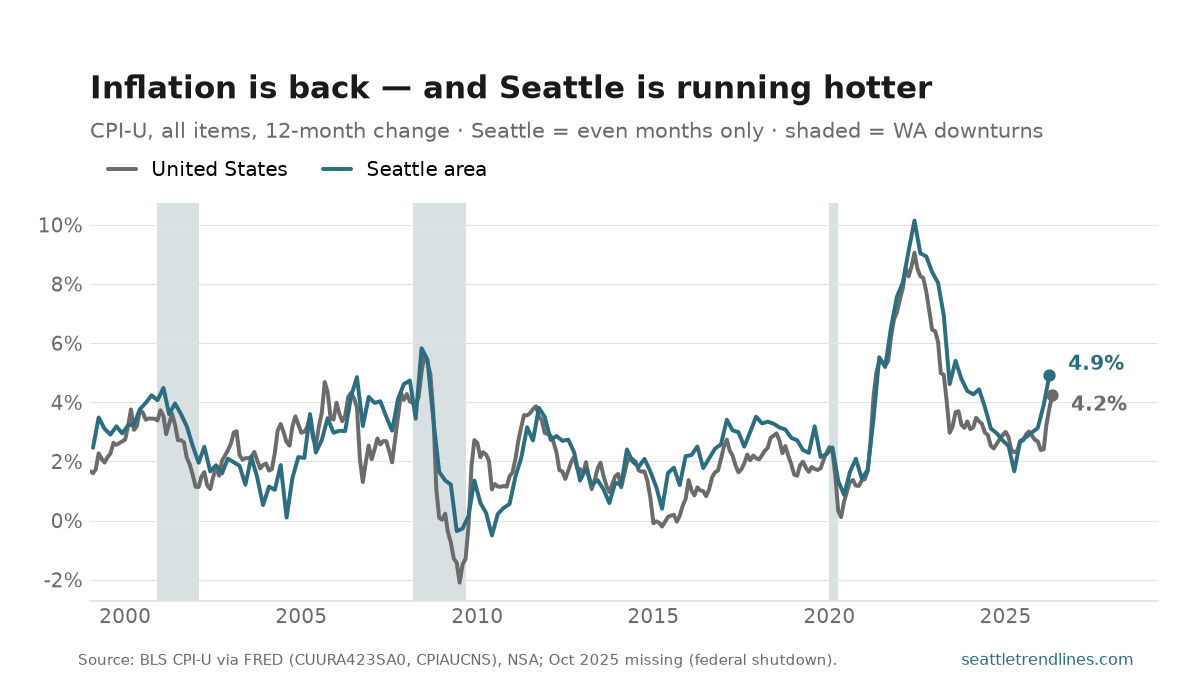
Consumer prices in the Seattle area rose 4.9% over the year through April — the fastest local inflation since November 2022, and the fifth straight reading to come in hotter than the last. The acceleration has been remarkably steady: 2.7% last June, 2.8% in August, 3.1% in December, 3.9% in February, 4.9% now. The U.S. rate is on the same escalator a step behind — 4.2% through May, up from 2.4% as recently as February.
Two things are true at once on this chart. First, the 2026 upturn is a national story with an energy signature — gasoline at record nominal prices does a lot of the lifting, just as it did in 2008 and 2022. Second, Seattle runs hot: the local line has sat above the national one for most of the past decade, it peaked higher in 2022 (10.1% vs 9.1%), and the current gap is about a point. Housing costs are the usual suspect in that persistent premium.
Reading notes, because this series has quirks. BLS surveys Seattle prices bimonthly — even months only — so the local line has half the resolution of the national one, and one recent point is simply missing (October 2025, a casualty of the federal shutdown). Both series are not seasonally adjusted, which is why we compare each month to the same month a year earlier rather than to the month before. And a city CPI measures price change within Seattle, not whether Seattle is cheaper or dearer than elsewhere — it answers “how fast,” never “how much.”
Source: U.S. Bureau of Labor Statistics, CPI-U, all items, not seasonally adjusted — Seattle-Tacoma-Bellevue (FRED CUURA423SA0) and U.S. city average (FRED CPIAUCNS). The June reading for both series lands with the CPI release in mid-July; this chart refreshes on the next daily build.
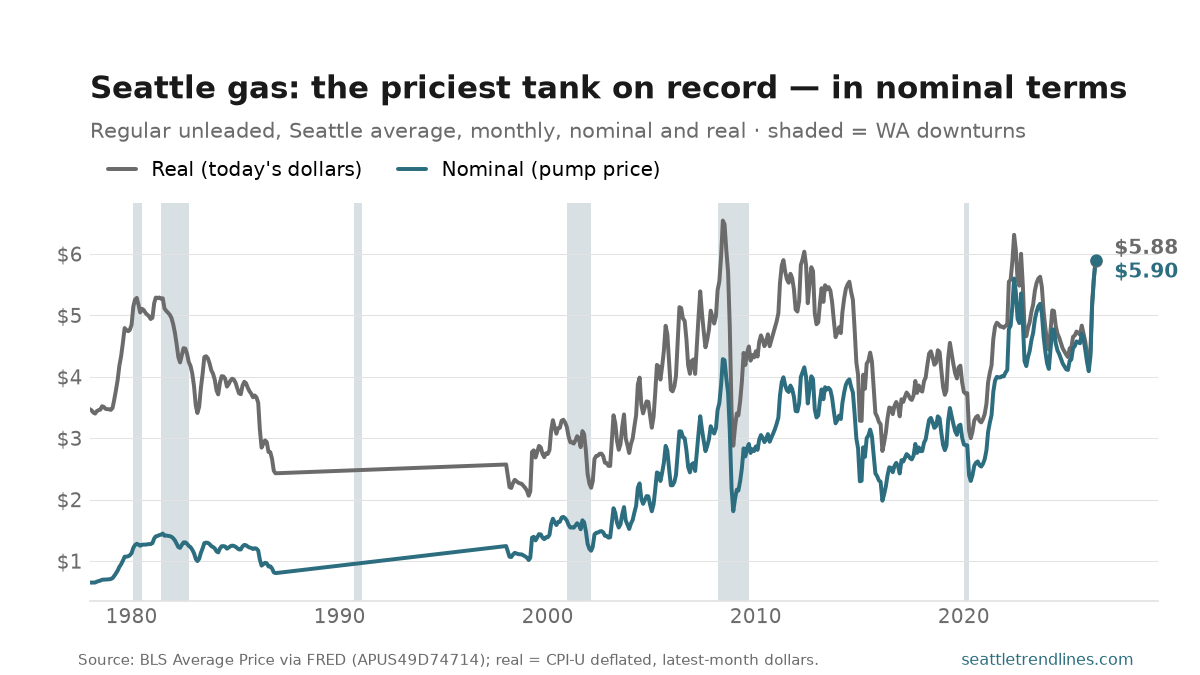
Seattle’s average pump price for regular unleaded hit $5.90 a gallon in May — the highest monthly figure in the 48 years BLS has tracked it, back to 1978, past the old record of $5.60 from June 2022. The run-up was violent: $1.81 in four months (January’s average was $4.09), the steepest four-month climb anywhere in the series — steeper than the ramps into 2008, into 2022, or out of the 1979 oil shock. And May isn’t the end of it — AAA’s daily tracking put King County above $6 in June.
The proximate causes are well documented: the war with Iran and the disruption of tanker traffic through the Strait of Hormuz have pushed crude sharply higher, the permanent closure of Valero’s Benicia refinery has tightened West Coast refining capacity, and Washington’s carbon-allowance program adds an estimated half-dollar per gallon on top. A supply shock landing on the country’s most supply-constrained fuel market, in one of its most heavily taxed states.
The gray line is the caveat that keeps the record honest: in real terms, this is expensive but not unprecedented. Deflated to today’s dollars, gas cost more during the 2008 spike (a peak of $6.57 in June), the 2011–2012 plateau (about $6.06), and the 2022 shock ($6.33 in June). May’s $5.90 sits about 10% under the real 2008 high — a record in the units your credit card sees, not yet in purchasing power. The long view sharpens the point: the 1979–80 oil shock, the last time a Middle East crisis did this to the pump, topped out in 1981 at the equivalent of only about $5.31 in today’s money — below where we are now. What felt ruinous to a driver in 1981 would be a relief today.
Gasoline is also the most visible piece of the broader inflation picture: it’s a small share of spending with an outsized grip on how expensive life feels. Adjusted for inflation, a gallon in 1978 ran about $3.49 — roughly $2.40 less than today’s tank, and a reminder of how much of the “record” is the dollar shrinking rather than gas alone climbing.
Source: U.S. Bureau of Labor Statistics, Average Price Data, gasoline, unleaded regular, per gallon, Seattle-Tacoma-Bellevue, via FRED series APUS49D74714, monthly since January 1978. Monthly average of posted prices — it smooths over the daily swings AAA reports. Real line deflated by U.S. CPI-U (CPIAUCNS) to the latest month. New months post with the CPI release, mid-month; this chart refreshes on the next daily build.
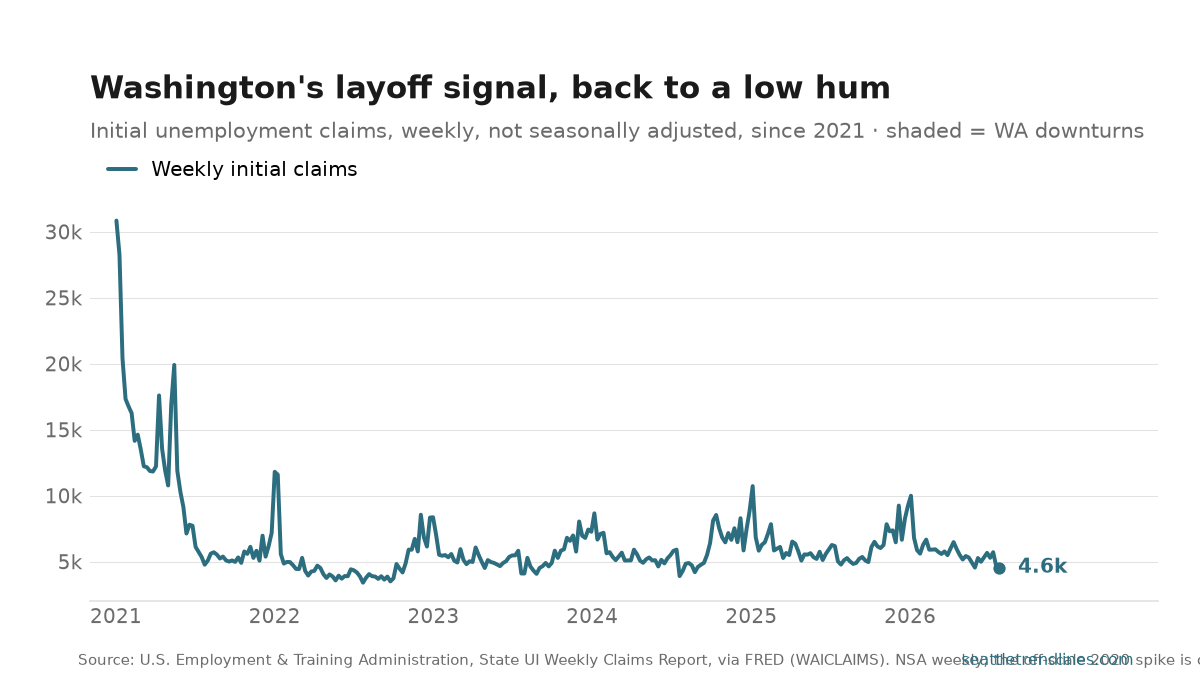
Most labor-market data arrives late. The monthly jobs report lands weeks after the fact; the unemployment rate is a lagging indicator by construction. Initial claims for unemployment insurance are the exception — filed the week someone loses a job, reported every Thursday, no smoothing. When layoffs turn, this is the first series to move.
The chart shows Washington’s weekly initial claims since 2021, past the off-scale spring-2020 spike (the week COVID closures hit, the state logged well over a hundred thousand claims in a single week — a value that flattens everything else if you leave it on the axis). What’s left is the signal that matters: the steady descent from the elevated 2021 readings back toward the low, calm range that defined the late-2010s labor market, and wherever the latest week now sits against it.
Read the level, but respect the noise. These are not seasonally adjusted, so the week-to-week sawtooth is mostly calendar — holidays, school-year edges, seasonal industries — not economic news. The honest way to watch this series is the trend across many weeks, and the direction relative to the same week a year earlier. A single spike is weather; a rising floor over a month or two is the thing to worry about.
Source: U.S. Employment & Training Administration, State UI Weekly Claims Report, via FRED series WAICLAIMS. Not seasonally adjusted; dated to the week ending Saturday. New claims post every Thursday around 5:30 a.m. Pacific; this chart refreshes automatically on the next daily build. State downturns shaded from FRED WAPHCI.