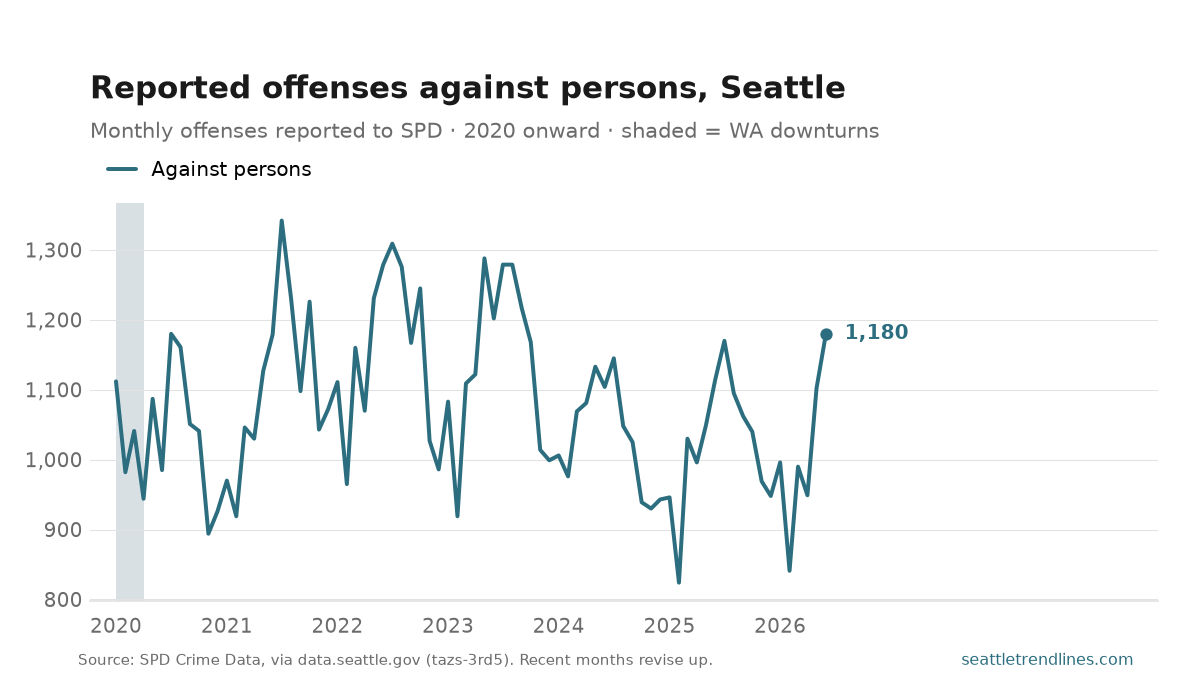
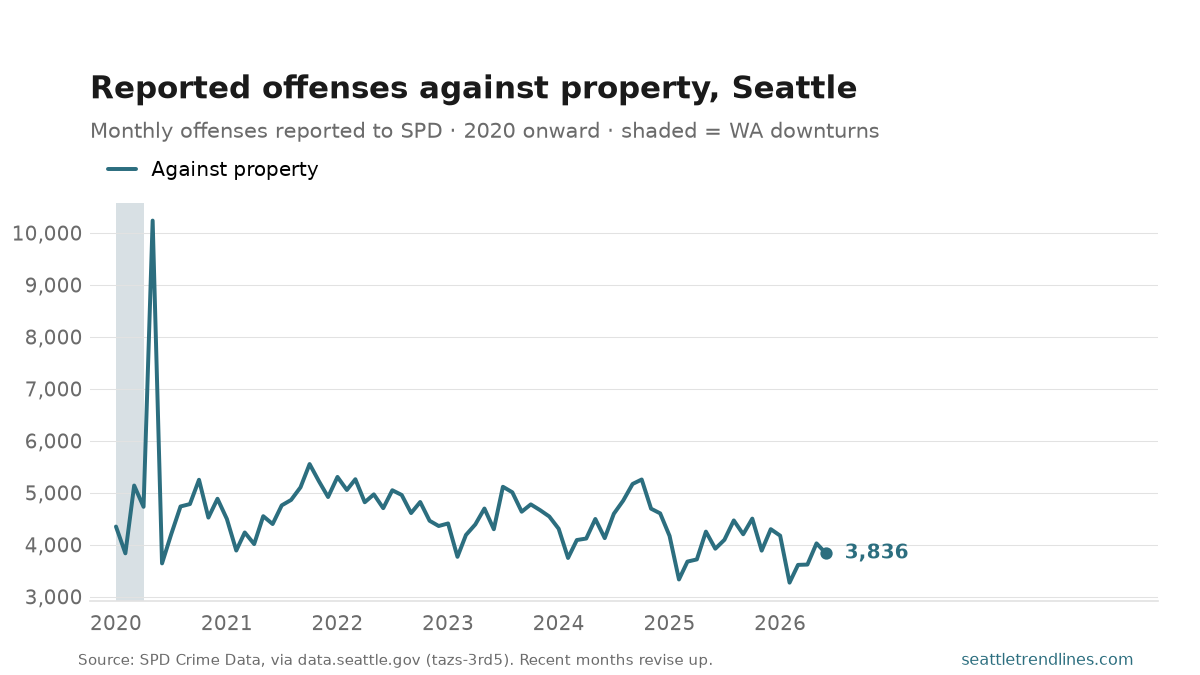
Seattle police recorded 5,748 offenses in July 2026, down 3.7% from a year earlier, across all four NIBRS crime-against categories. The charts above draw the two largest, one each: property offenses outnumber offenses against persons by roughly three to one, so on shared axes the persons line barely moves and a single ‘crime’ line mostly tracks car prowls.
Three caveats, and they matter more than the number. This counts crime reported to police, so it moves with reporting behaviour as well as with crime. It counts offenses, not incidents, and one report can carry several. And the most recent months revise upward as late reports land, so treat the right-hand edge as provisional. The chart starts in 2020 because SPD migrated records systems in 2019 and the counts on either side of that are not comparable.
Source: Seattle Police Department, SPD Crime Data 2008-Present, via data.seattle.gov (Socrata tazs-3rd5). Offenses dated by when the offense started. Auto-generated each build.
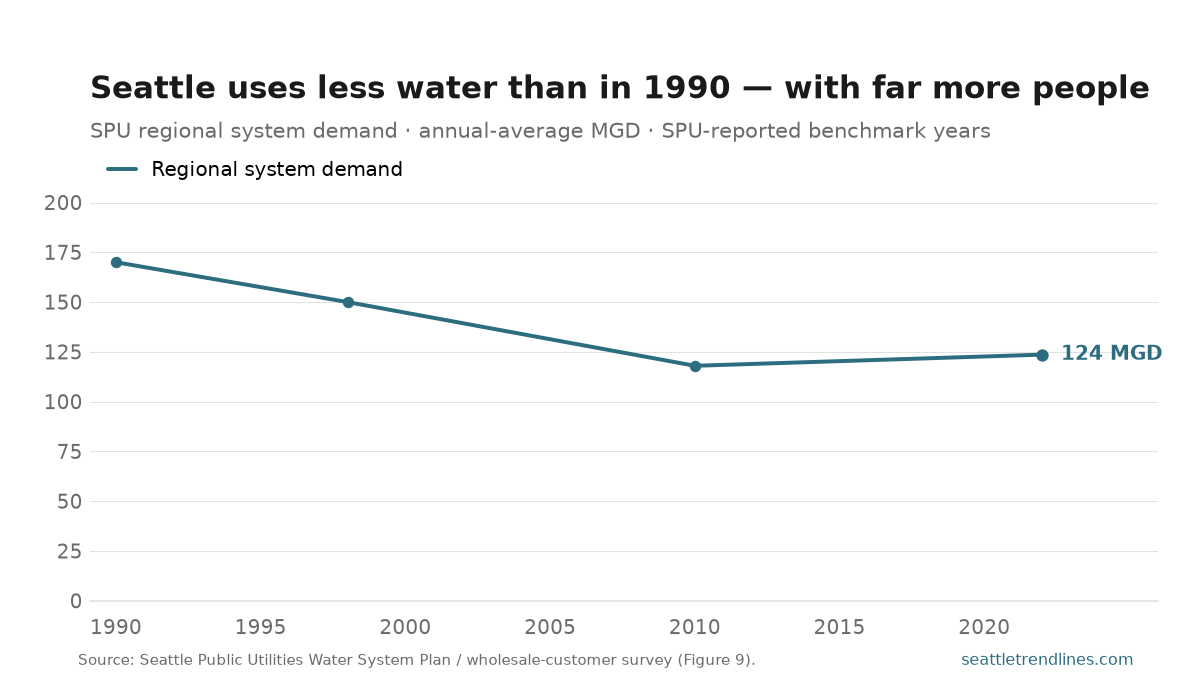
Most infrastructure stories in a growing city are about more: more housing, more transit, more power. Water is the exception. The Seattle regional system — the Cedar and Tolt supply that Seattle Public Utilities runs for about 1.5 million people across the metro — delivered roughly 170 million gallons a day in 1990. By 2022 it was down to about 124 even as the population it serves grew by around 44%. Total demand fell about 27% while the customer base swelled; per-person use is roughly half what it was in 1990. SPU’s own framing: the region now uses less water in total than it did in 1957.
The decline wasn’t gradual erosion so much as a step change that stuck. Demand sat on a plateau near 170 through the late 1980s, then the 1992 drought forced mandatory curtailment and broke the habit. What kept it broken was structural: the 1993 plumbing code (low-flow toilets, showerheads, and faucet aerators), progressively efficient appliances, a sustained regional conservation program, rising water rates that made waste expensive, and tighter system operations that cut leakage and reservoir overflow. Demand bottomed near 118 in 2010 and has drifted up only slightly since — into the low 120s — as population growth finally began to outrun the efficiency gains.
Why it matters beyond the utility bill: a region that added nearly half again as many people while cutting total water use has effectively manufactured new supply out of conservation, deferring the cost of new dams or bigger withdrawals — and leaving more water in the rivers, which is its own kind of dividend for the salmon. One honesty note on the chart: SPU publishes the full annual series only as a graphic, so the points plotted here are its reported figures at benchmark years, not a continuous meter read — the shape is right, the exact path between dots is SPU’s, not mine.
Source: Seattle Public Utilities — Water System Plan and annual wholesale-customer survey (Figure 9, Population & Components of Water Demand). Annual-average demand on the SPU regional supply system. SPU reports the full series only as a chart; values shown are its stated benchmark figures. Annual.
Boeing is still the Puget Sound’s largest manufacturing employer, and its monthly delivery count is the cleanest read on how busy the region’s assembly lines are. In June 2026 the company delivered 64 commercial airplanes: 50 737 MAX jets, 10 787-9 Dreamliners, three 767s, and one 777 Freighter.
Of those 64, 54 were assembled in Washington — the 737 in Renton, the 767 and 777 in Everett. The ten 787s are built in North Charleston, South Carolina, the one widebody line Boeing moved out of the region. So June’s tally is really 54 Puget Sound airplanes plus ten from the Carolinas.
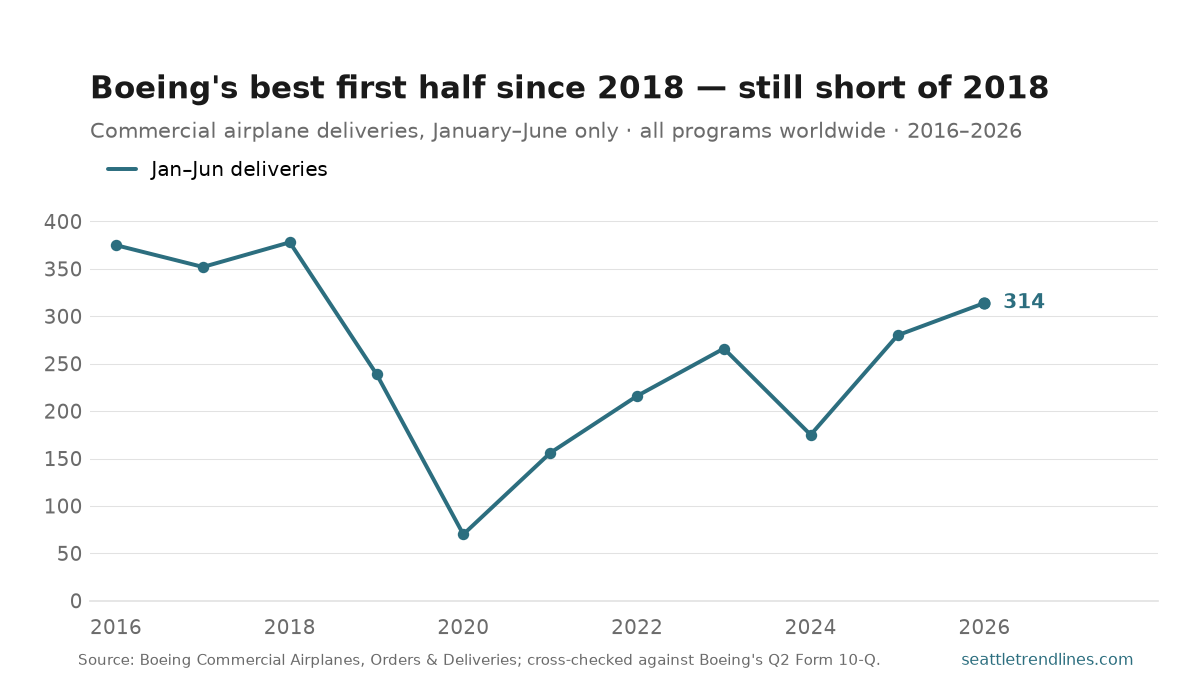
June brought Boeing’s second-quarter total to 171 jets and its first-half total to 314 — up 12% from the first half of 2025 and the company’s best first half since 2018, as 737 MAX output keeps climbing back from the strike- and quality-related slowdowns of 2024. The order book stayed deep: 121 gross orders in June, 445 gross (386 net) for the half, and a backlog of 6,202 aircraft at month-end — years of work for the region’s aerospace payrolls.
The chart is why “best first half since 2018” is both true and a smaller claim than it sounds. Boeing’s January–June count collapsed twice inside six years: to 239 in 2019, when the 737 MAX was grounded that March, and to 70 in the first half of 2020, when the airlines stopped taking airplanes at all. The climb back has been anything but a straight line — 156, then 216, then 266 in 2023, then a slide to 175 in the first half of 2024 after the January door-plug blowout put a regulator’s cap on MAX output. Two strong halves have followed. But the pre-grounding plateau was 375, 352 and 378 in 2016, 2017 and 2018. At 314, Boeing is still running about 17% below its 2018 pace. This is a recovery, not a return.
One caveat on reading the chart as a Puget Sound indicator: it counts every Boeing commercial delivery worldwide, the North Charleston 787s included, because that is the only basis on which the company reports the number consistently. The first-half 314 breaks down as 243 737s, 40 787s, 16 767s and 15 777s, so 274 of the 314 — 87% — were assembled in Washington, a slightly higher local share than June’s 54-of-64 (84%). The line’s shape — grounding, pandemic, door plug, recovery — is the Renton and Everett story. Its level runs about 15% above the region’s own count.
Source: Boeing Commercial, Orders & Deliveries (monthly, company IR). June 2026 program detail via Air Data News; first-half context via CNBC. Chart series: January–June deliveries by year, hand-pulled from Boeing’s monthly O&D summaries and cross-checked against the six-month delivery tables in Boeing’s Q2 Form 10-Q filings (data/boeing-h1-deliveries.csv carries the per-year citation). Final-assembly locations: 737 (Renton, WA), 767 and 777 (Everett, WA), 787 (North Charleston, SC). Boeing reports July deliveries in mid-August.
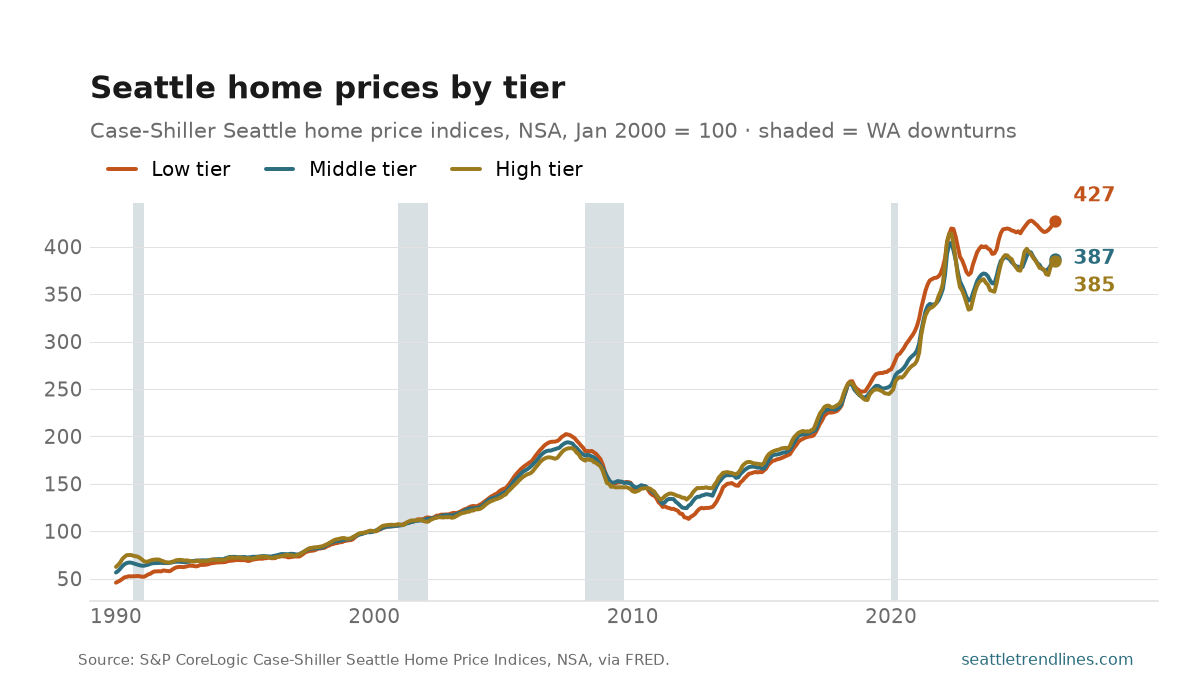
The Case-Shiller Seattle home price index read 393.2 in June 2026 — down 1.9% from a year earlier, and 3.9× its January 2000 level. The three tiers are the part worth watching: S&P splits the metro’s repeat sales into thirds by price, and the cheapest third has pulled steadily away from the most expensive third since 2012. Case-Shiller is a three-month average reported with a two-month lag, so it is the slowest of the local price measures — and the most methodologically careful.
Source: S&P CoreLogic Case-Shiller Seattle Home Price Indices, not seasonally adjusted, via FRED (SEXRNSA, tiers SEXRLTNSA / SEXRMTNSA / SEXRHTNSA). January 2000 = 100. Auto-generated each build.
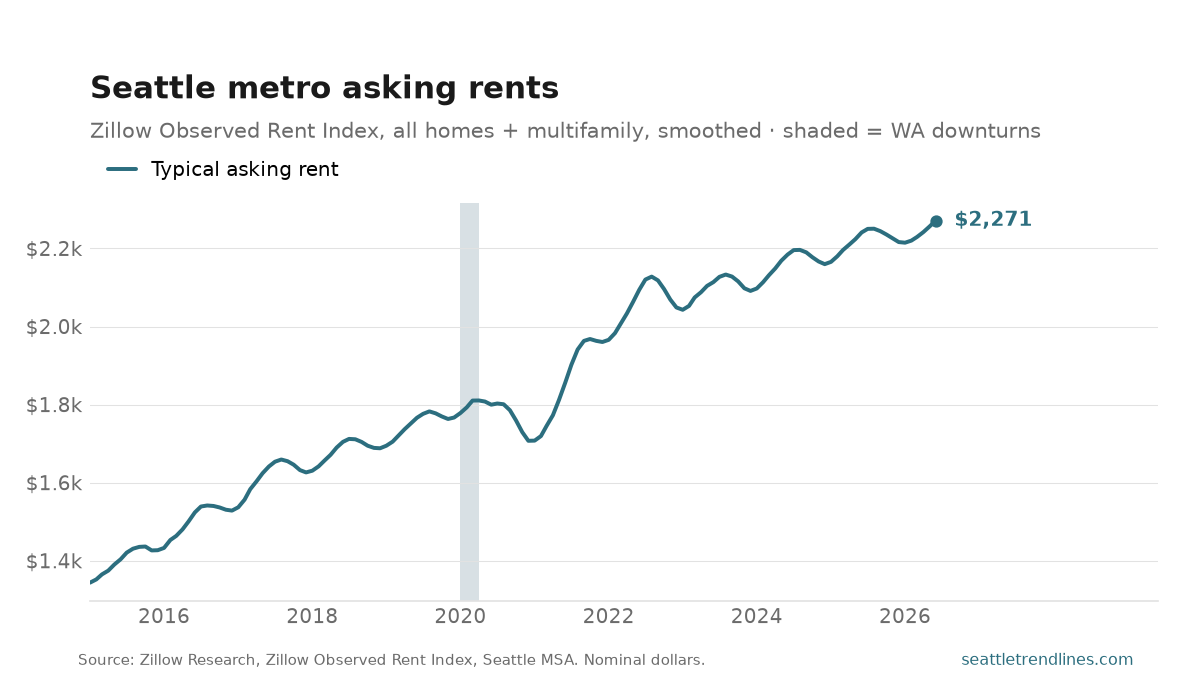
The typical asking rent in the Seattle metro was $2,261 a month in June 2026, up 1.3% from a year earlier. ZORI tracks new leases, not the average rent paid across all tenants, so it turns roughly a year before the rent component of the local CPI does — which makes it the leading indicator of the two. Nominal dollars.
Source: Zillow Research, Zillow Observed Rent Index (ZORI), Seattle–Tacoma–Bellevue MSA, smoothed, all homes plus multifamily, nominal dollars. Auto-generated each build.
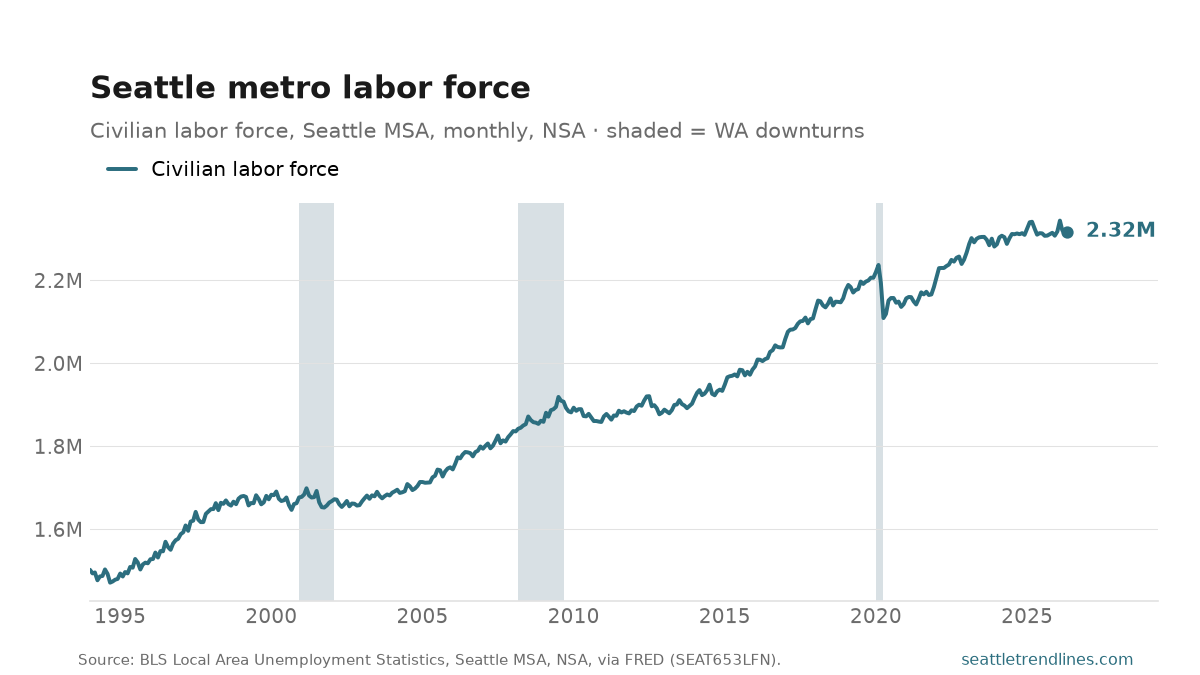
The Seattle–Tacoma–Bellevue labor force — everyone employed or actively looking for work — was 2,317,646 in May 2026, up 0.3% from a year earlier. It’s the head-count denominator under the unemployment rate: a labor force that grows with population and participation. Not seasonally adjusted.
Source: U.S. Bureau of Labor Statistics, Local Area Unemployment Statistics, Seattle–Tacoma–Bellevue MSA civilian labor force, not seasonally adjusted, via FRED SEAT653LFN. Auto-generated each build.
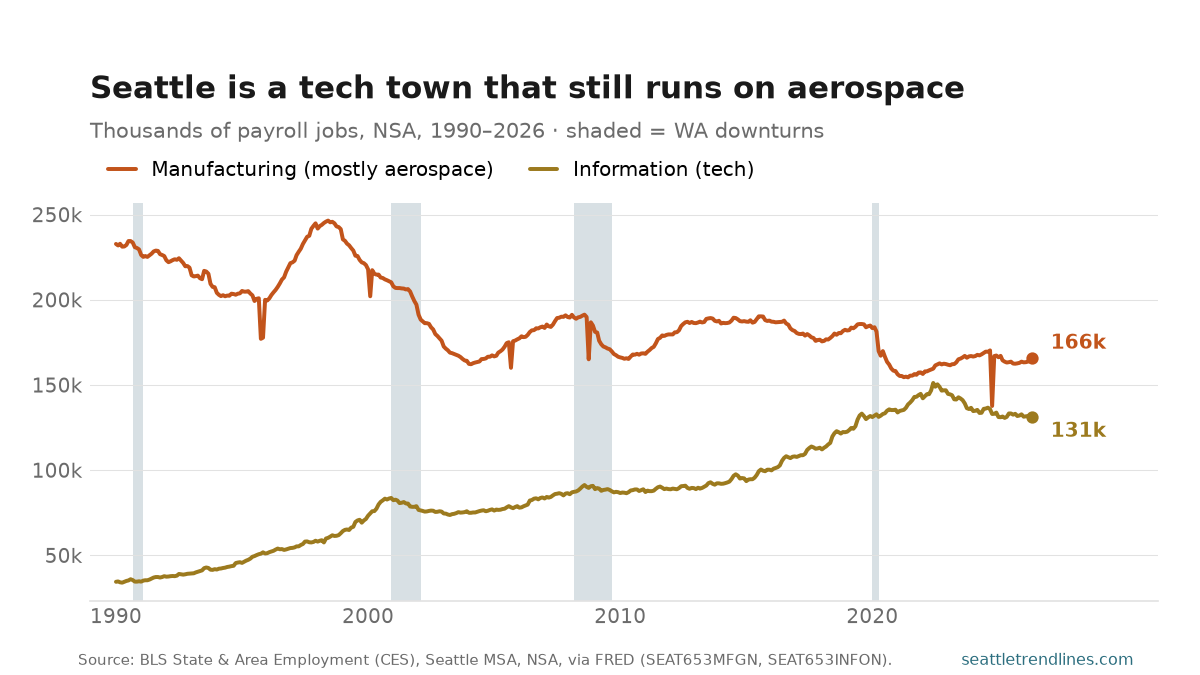
Seattle sells itself as a tech town — Amazon, Microsoft, a cloud on every résumé. But payrolls tell a stubborner story. In May 2026 the Information sector — software, publishing, telecom, the closest thing the official data has to “tech” — employed 131,200 people across the metro. Manufacturing, which here is overwhelmingly Boeing and its aerospace supply chain, employed 165,800. Aerospace still out-hires tech by about 35,000 jobs, and despite thirty-six years of Seattle becoming synonymous with software, these two lines have never crossed.
They have, however, spent a generation closing. In 1990 it wasn’t close: manufacturing employed 232,800 and Information just 34,500 — a gap of nearly 200,000. Information then climbed almost without interruption for three decades, the Microsoft-then-Amazon ascent, peaking near 151,200 in June 2022. Since then it has fallen for three straight years to 131,200, off about 13% from that peak — the local fingerprint of the 2023–2025 tech retrenchment. Manufacturing ran the opposite way: down about a third from its 246,500 high in 1998, with the violent single-month notches — 1995, 2005, 2008, and again in October 2024 — marking Boeing machinist strikes, visible because the series isn’t seasonally adjusted. The 2024 strike alone dropped the line to 137,700 before it snapped back.
The right edge is the surprise. Over the past year the town’s identity and its payroll data point in opposite directions: tech was flat (Information −0.1% year over year) while aerospace grew (manufacturing +1.6%), lifting the sector off its strike-year floor. So the convergence that looked inevitable for thirty years has stalled — not because tech overtook aerospace, but because aerospace stopped falling and tech stopped rising. Whether the crossover ever happens now depends less on Amazon than on Boeing’s order book.
One caveat on the labels. There is no clean monthly “aerospace” series for the metro, so this uses total manufacturing as the stand-in; in the Seattle MSA that is a fair proxy — aerospace dominates the sector — but it also sweeps in a tail of food, shipbuilding, and other production. “Information” likewise undercounts tech, since plenty of software work is booked under professional services. The levels are proxies; the shapes — one sector cresting and rolling over, the other grinding down and flattening — are the real story. For the fuller sector picture, see the jobs-by-sector breakdown.
Source: U.S. Bureau of Labor Statistics, State & Area Employment (CES), Seattle–Tacoma–Bellevue WA MSA, not seasonally adjusted, via FRED — Manufacturing and Information. Thousands of jobs, dated to the first of the month. New months post about three weeks after month-end; this chart refreshes on the next daily build.
The Ports of Seattle and Tacoma compete no longer: in 2015 they merged their marine-cargo operations into The Northwest Seaport Alliance (NWSA), which since then reports the two harbors as one gateway. So this is a single combined line — there is no public Seattle-versus-Tacoma container split after 2015.
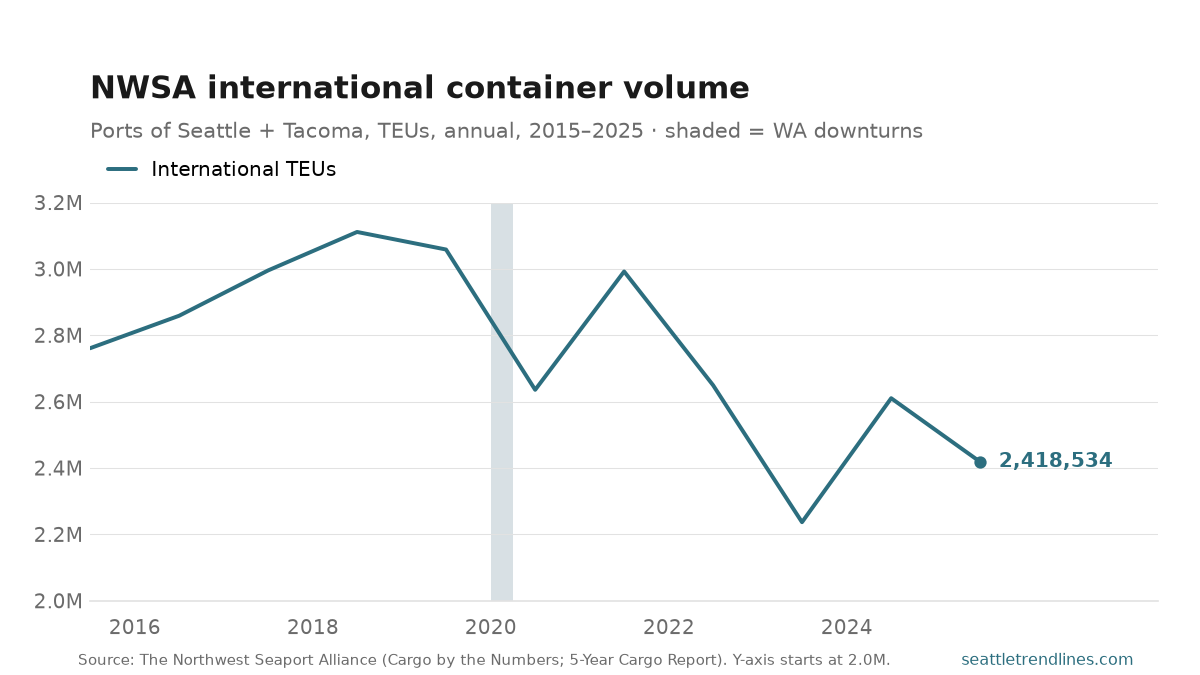
NWSA handled 2,418,534 international TEUs in 2025, down 7.3% from 2024. That is the second-lowest annual total since the 2015 merger — above only the 2.24 million trough of 2023 — and it leaves container volume 22% below the 2018 peak of 3.11 million and 13% below where it stood in 2015.
The shaded band marks Washington’s only economic contraction of the period, the early-2020 COVID downturn. Unlike the city’s population, the docks felt it: international volume dropped 13.8% in 2020. It then snapped back in the 2021 import boom to 2.99 million, before three of the next four years moved lower as imports normalized and 2025’s tariff pressure and elevated retail inventories cut into the full-container trade.
Splitting the loaded boxes apart shows two different stories.
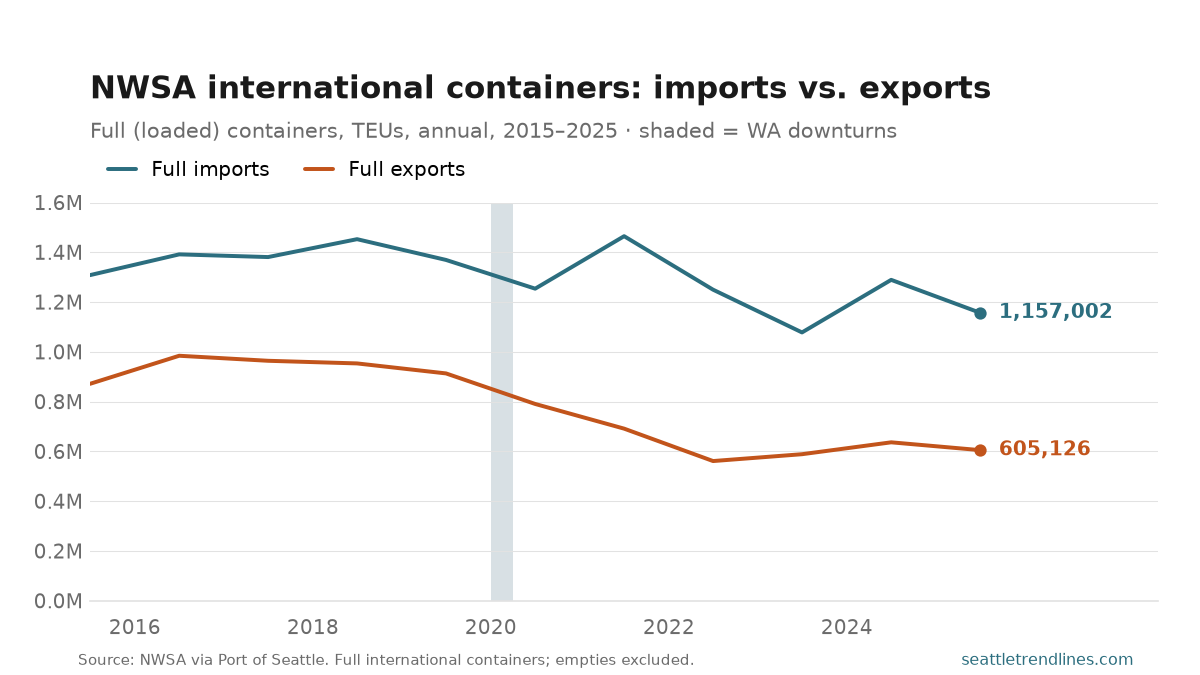
Full imports have held in a 1.1–1.5 million band: they spiked to 1.46 million in the 2021 import boom, then unwound, falling 10.3% in 2025 to 1,157,002. Full exports have done something more durable — drifted down for a decade, from a 2016 peak of 984,274 to 605,126 in 2025 (−4.9% on the year), a 39% slide from that peak. The result: the gateway’s import-to-export ratio has widened from 1.5 in 2015 to 1.9 today, and in recent years NWSA now ships back more empty boxes than it fills with exports.
Two caveats on the number. It counts international containers only — full imports, full exports, and empties — and excludes domestic Alaska and Hawaii traffic of roughly 0.73 million TEU a year; including it, NWSA’s 2025 grand total was about 3.16 million, down 5.5% on the year. And because the ports report jointly, the long Seattle-versus-Tacoma rivalry that ran through the 1990s and 2000s can no longer be drawn as two lines.
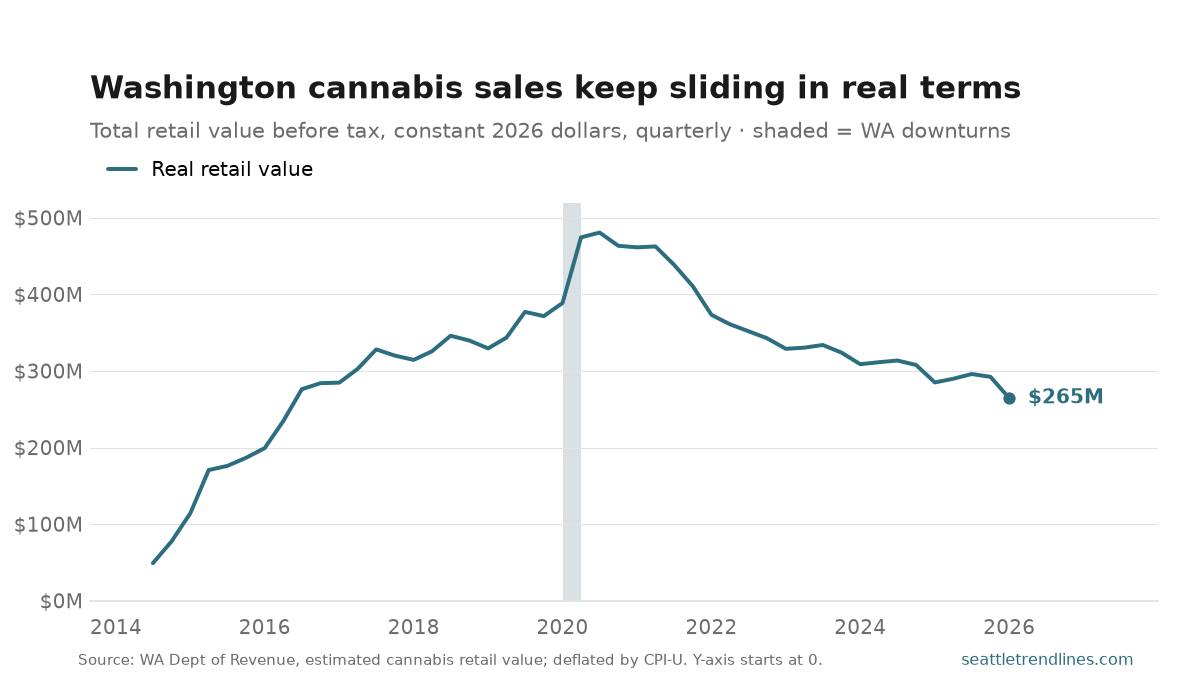
Legal cannabis arrived in Washington in July 2014. In today’s dollars, sales went almost straight up for six years — from $49M in the first quarter to a peak of $481M in 2020 Q3 — and have been sliding ever since. The latest reading, $265M in 2026 Q1, is 45% below that peak and down 7.2% from a year earlier. (All figures here are inflation-adjusted to constant 2026 dollars; in unadjusted dollars the peak was a smaller-looking $381M and the drop from it about 31%.)
The 2020 spike was real: cannabis was deemed essential, stores stayed open, and stuck-at-home demand pushed real sales up about 27% year-over-year. The shaded band marks Washington’s only economic contraction inside this window — the 2020 COVID downturn — and cannabis is the rare series that climbed straight through it. But the boom didn’t outlast the pandemic. In real terms, annual sales peaked at $1.81 billion in 2020 and have fallen every year since, to $1.16 billion in 2025.
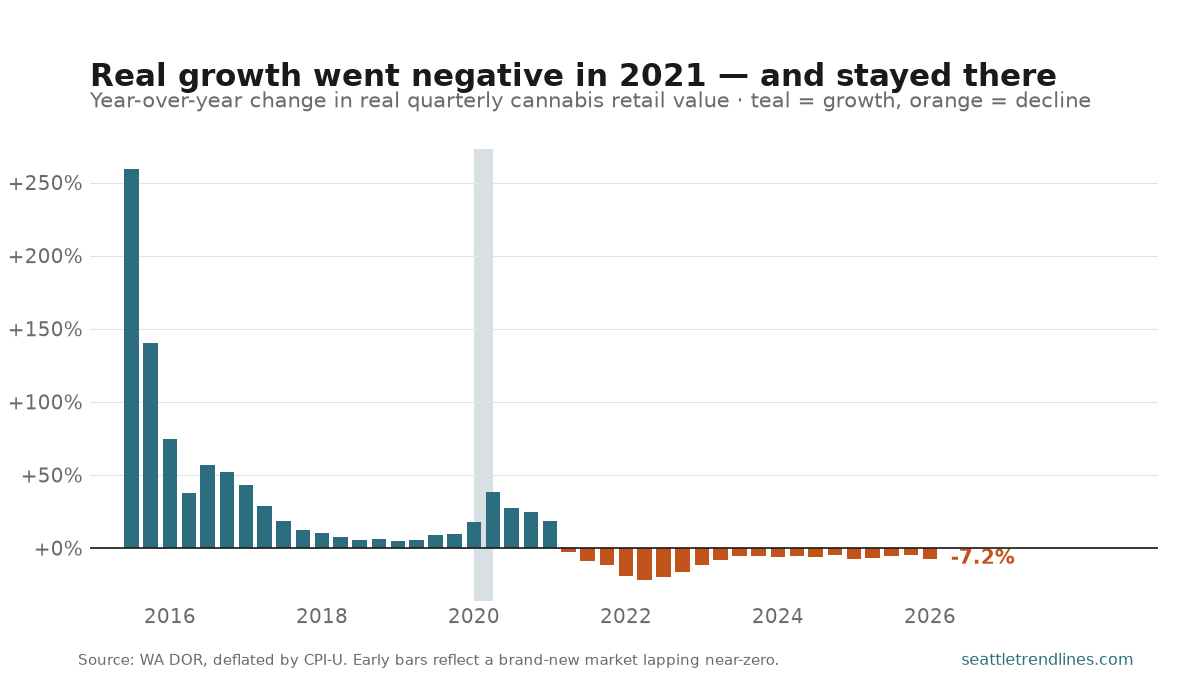
That is the real story: adjusted for inflation, Washington’s cannabis market has shrunk year-over-year for 20 straight quarters — every quarter since spring 2021. Nominal dollars hide it, because rising prices flatter the recent numbers; the unadjusted series is “only” down about 31% from peak. Falling retail dollars also understate what’s moving off the shelf — Washington’s per-gram cannabis prices have dropped sharply since 2014, so the state is almost certainly selling far more product for that shrinking pile of money.
One structural break is worth flagging. Through mid-2016 the series blends two channels: licensed I-502 recreational stores and medical “collective gardens.” The Cannabis Patient Protection Act shut the collectives down on July 1, 2016, folding medical patients into the licensed retail system — which is why the early-2016 composition shifts even as the total keeps climbing.
Across nearly twelve years, Washington’s legal market has rung up about $14.7 billion in retail sales measured in today’s dollars (roughly $12.3 billion unadjusted).
Source: WA Department of Revenue, “Recreational and medical cannabis taxes” — Estimated Sales Tax Collected on Sales of Cannabis (XLSX), quarterly total retail value before tax, prepared by DOR’s Research & Fiscal Analysis Division. Deflated to constant 2026 dollars using CPI-U, U.S. city average, all items, NSA (BLS: CUUR0000SA0). The 37% cannabis excise tax is administered by the WA Liquor and Cannabis Board. Quarterly; DOR states each quarter is static and not revised. Next update: DOR posts 2026 Q2 in roughly August 2026.
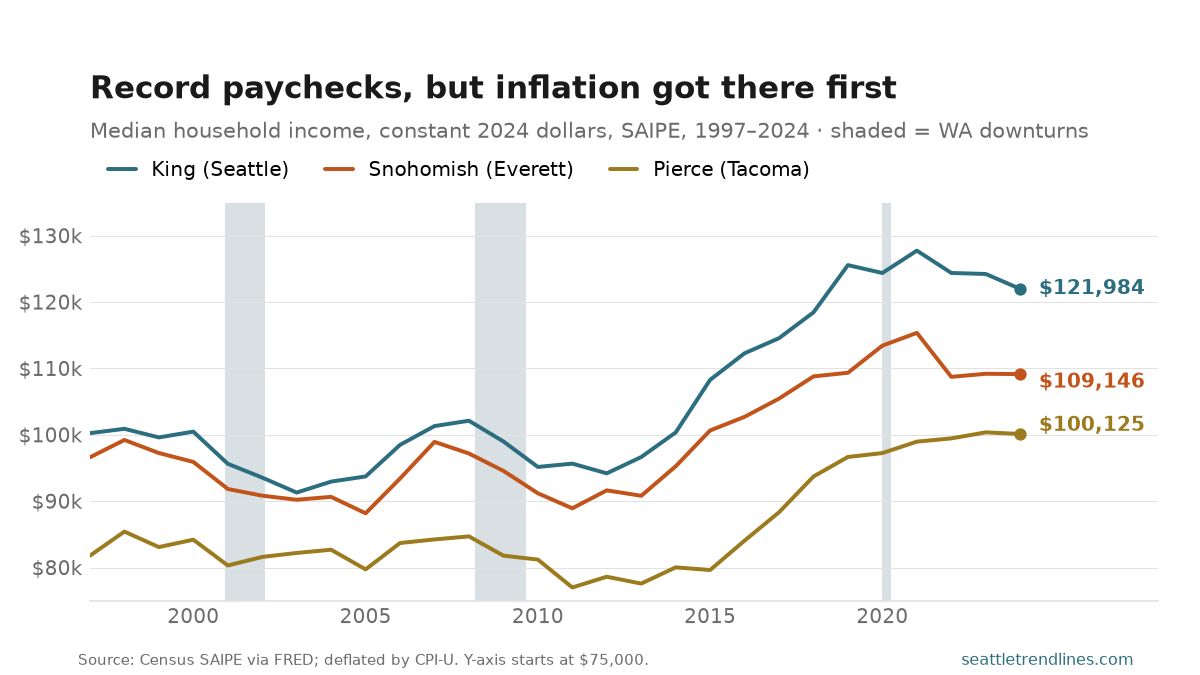
The headline number keeps setting records. King County’s median household income reached $121,984 in 2024 — the highest in the SAIPE series, and up about 1% on the year in plain dollars. Pierce ($100,125) and Snohomish ($109,146) also printed nominal records.
Adjust for inflation and the picture inverts. In constant 2024 dollars, King County’s median income peaked in 2021 at about $128,000 and has fallen every year since — to $124,400, then $124,200, and now $122,000, about 4.5% below the peak. The 2024 reading is a 1.8% real decline even as the nominal figure rose: prices simply went up faster than the median paycheck. Snohomish traces the same arc from its own 2021 peak; Pierce, the late bloomer, didn’t peak until 2023 and has roughly held there.
Step back and the long sweep is two different eras. From the late-1990s through 2012, real median income in King County went nowhere — by 2012 it was about $94,000 in today’s dollars, actually below its 1997 level of roughly $100,000, with the dot-com and Great Recession downturns bracketing a lost decade and a half. Then the cloud-and-platform boom hit: real income climbed more than a third from the 2012 trough to the 2021 peak. The recent slip is small against that run, but it is the first sustained real decline since the recovery began — and with local inflation back near 5%, the 2025 estimate will have a high bar to clear.
The county ranking has barely budged. King has paid the most throughout, running about 22% above Pierce in both 1997 and 2024 — three decades of growth that lifted all three counties without rearranging them.
Source: U.S. Census Bureau, Small Area Income and Poverty Estimates (SAIPE), median household income, retrieved via FRED (King, Pierce, Snohomish). SAIPE are model-based single-year estimates; values are dated to the income year. Inflation adjustment uses the CPI-U (U.S. city average, all items, NSA, annual average), constant 2024 dollars. State downturns: Philadelphia Fed Coincident Economic Activity Index for Washington. SAIPE 2024 estimates were released in December 2025; the 2025 vintage is due around December 2026.