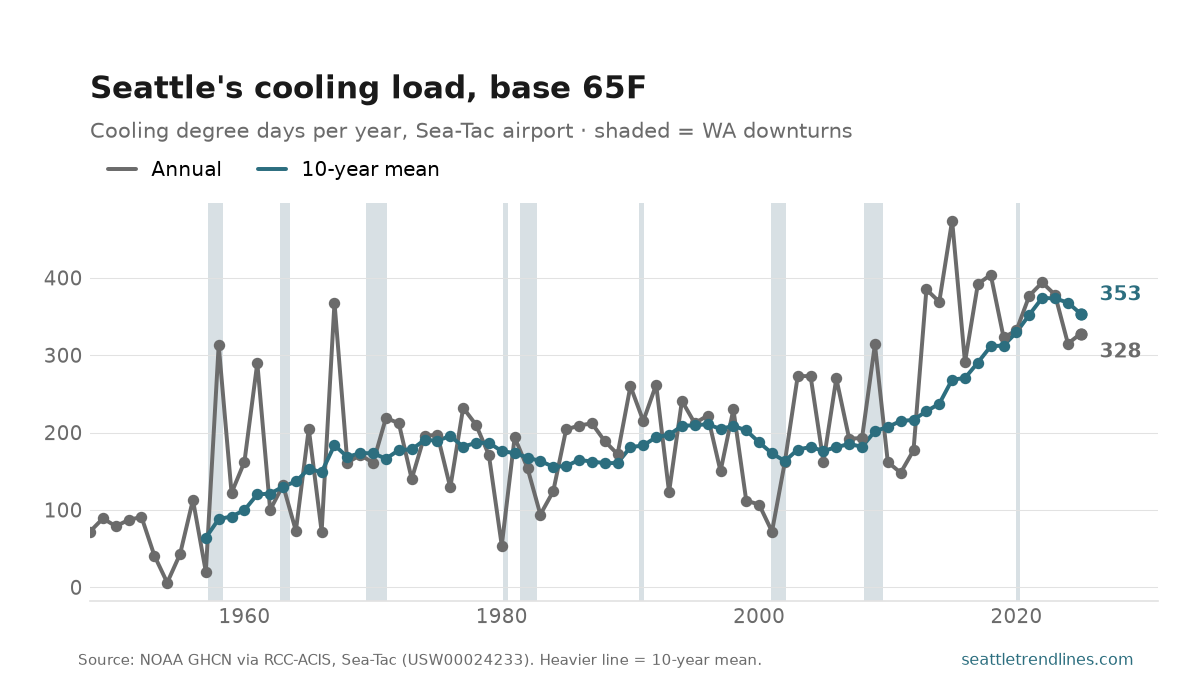
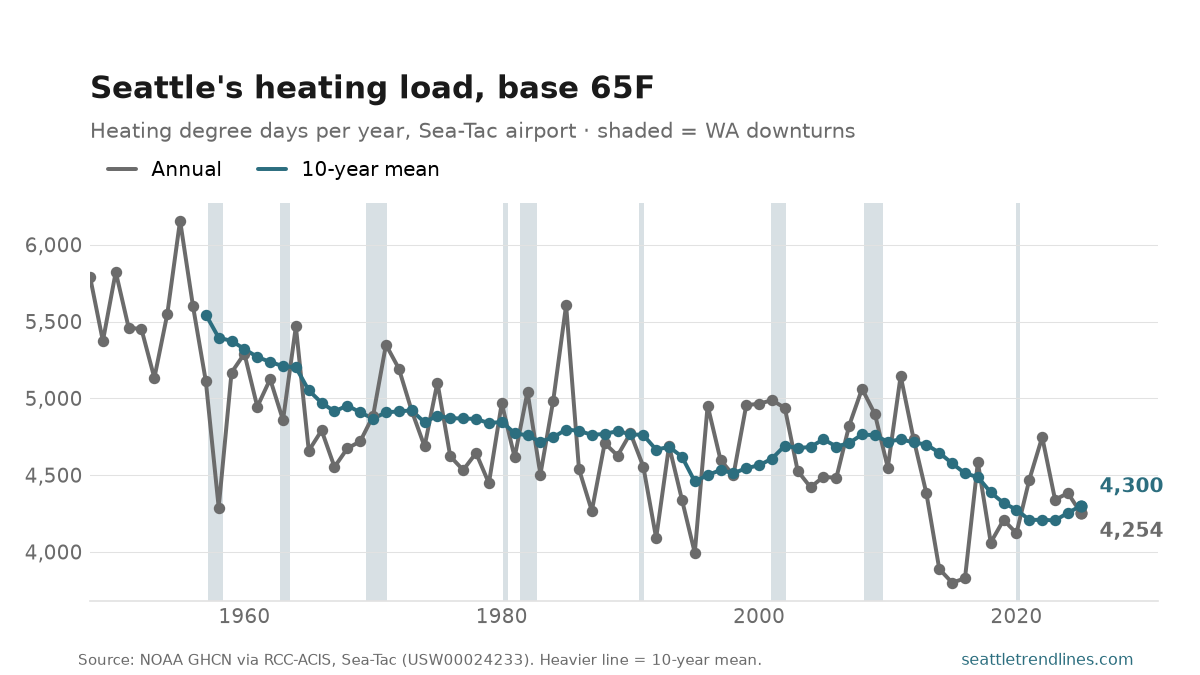
Sea-Tac ran up 328 cooling degree days in 2025 and 4,254 heating degree days. A degree day is one degree of gap between the day’s mean temperature and 65°F, summed over the year — a rough measure of how hard a building has to work, and the number utilities plan around.
The cooling side is the one that moved. Averaged over ten years to smooth the summers out, cooling degree days have gone from 64 in the decade ending 1957 to 353 in the decade ending 2025 — about 5.5 times what it was. That is the number behind every story about air conditioning arriving in a city that was built without it. The single worst year on record was 474 in 2015; the mildest was 6 in 1954.
And yet the building’s total work went down, not up. Heating degree days fell from 5,545 to 4,300 across the same span — a drop of 1,245 against a cooling rise of only 289. Seattle is a heating city with a warming climate, so the furnace saves far more than the air conditioner spends. That is a statement about degrees, not about energy: the two loads are not interchangeable — heat here is largely gas and electric resistance in winter, cooling is electricity on the summer afternoons when the grid is tightest. A smaller total load can still mean a higher peak.
The station is the caveat, and it is the same one the monthly Sea-Tac anomaly post carries. Sea-Tac is the only continuous daily record here back to 1948, and it is an airport with a great deal more tarmac around the thermometer than it had then. Some of the cooling-side climb is the airport growing rather than the region warming. Unlike the anomaly series, degree days have no fixed baseline to protect them from that — they are absolute counts — so read the direction rather than the decimal. Only complete calendar years are charted.
Source: NOAA Global Historical Climatology Network daily records for Seattle-Tacoma International Airport (USW00024233), retrieved through RCC-ACIS, degree days base 65°F summed over each complete calendar year. Bench post — generated from the latest observation in the site database.
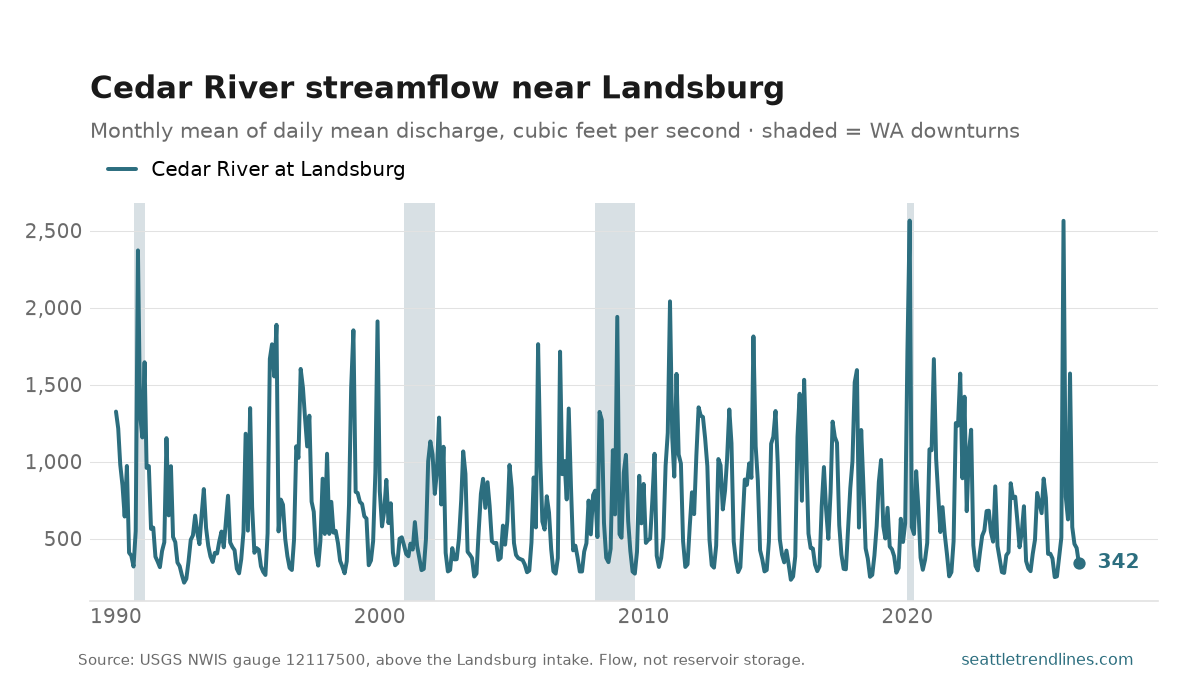
The Cedar River ran at 342 cubic feet per second in July 2026, measured just above the Landsburg intake that supplies about two thirds of Seattle’s drinking water. That is what arrives, before the city takes its share.
That is 85% of the July average, which is the only comparison worth making. This is a rain-and-snowmelt river, so the sawtooth in the chart is the season rather than the supply: every year is high in winter and low in September, and a wet January says nothing about whether there will be enough in August. Across 37 years, July has averaged 404 cfs — the driest was 263 (1992) and the wettest 674 (1997). The late-summer low is the number that decides anything, because that is when the city is living on what the winter banked.
This is half of the water-supply picture, and the missing half is storage. Chester Morse Lake and the Masonry Pool are what carry the city from the last of the snowmelt to the first autumn rain, and neither reservoir publishes a machine-readable level — so this post charts the flow and says plainly that it cannot tell you how full the tank is. The snowpack post upstream of this one is the other leading indicator, through the winter, and it runs December to May. Recent months are provisional and get revised.
Source: U.S. Geological Survey, NWIS daily values, gauge 12117500 (Cedar River near Landsburg, WA), monthly mean of daily mean discharge. Measured above the Landsburg intake, so it is inflow rather than what the city withdraws. Bench post — generated from the latest observation in the site database.
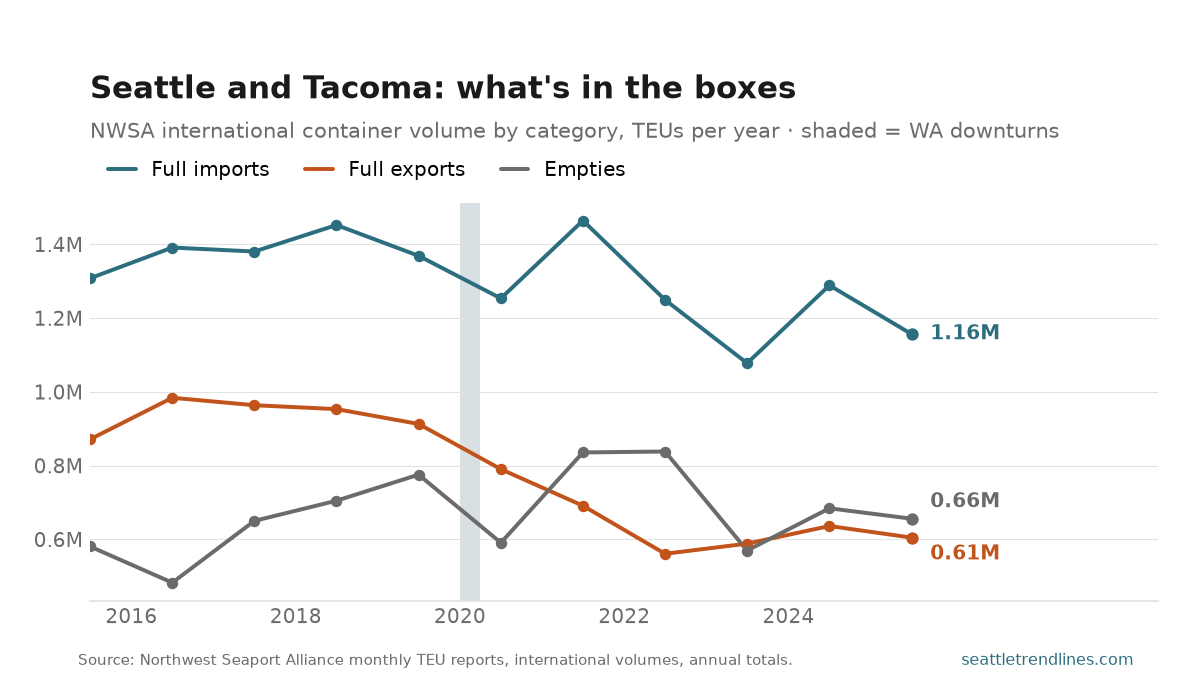
The Northwest Seaport Alliance moved 1,157,002 TEUs of full imports in 2025, down 10.3% on the year, against 605,126 TEUs of full exports and 656,406 TEUs of empty boxes.
The headline container number adds those together, and in doing so hides the thing worth knowing: for every container of goods leaving Seattle and Tacoma, roughly 1.9 arrive. The balance did not use to be that lopsided. Exports have fallen while imports have held, and the difference has to sail back out as air — which is why the empties line matters. An empty container is a paid movement of nothing, and its share of the total is a direct measure of how one-directional this gateway has become.
International volumes only, so the Alaska and Hawai’i domestic trades are excluded. TEUs count boxes rather than value, so a container of aircraft parts and a container of hay weigh the same here. Annual figures — the Alliance reports monthly, but only the year totals are wired into this site.
Source: Northwest Seaport Alliance container volume reports, international full imports, full exports and empty containers, annual totals in TEUs. Auto-generated each build.
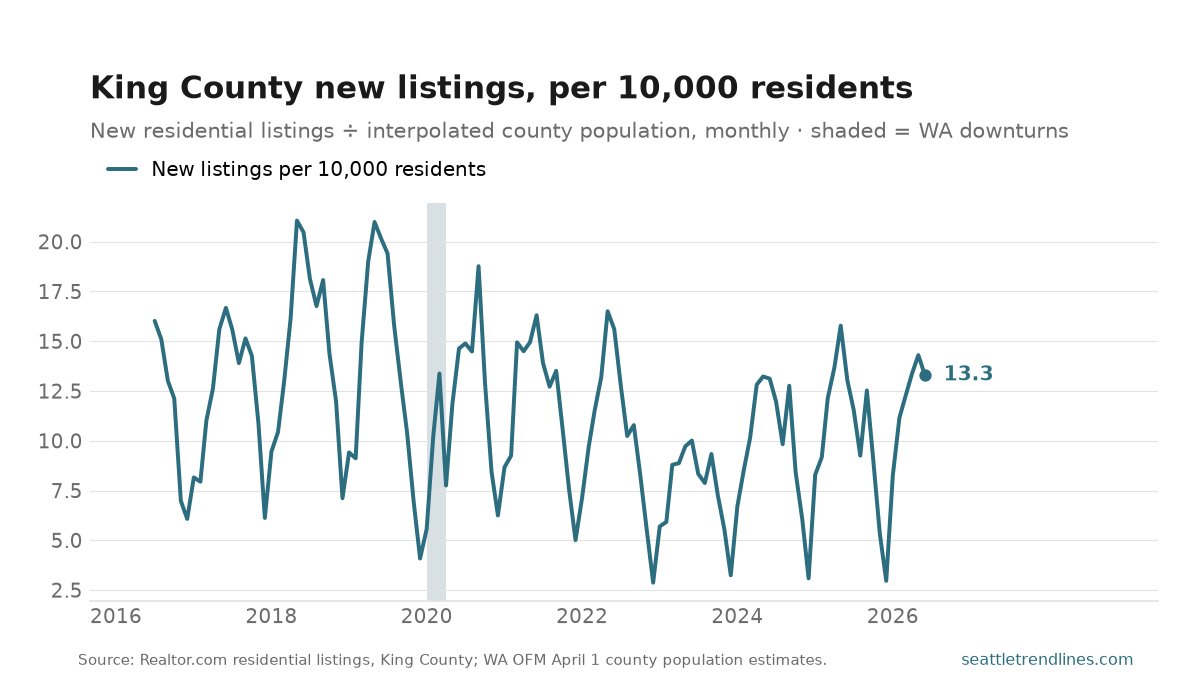
King County sellers listed 2,512 homes in June 2026 — 13.3 per 10,000 county residents, up 1.9% on the year as a rate.
Per head is what makes this series comparable across a decade, because King County in June 2026 holds a few hundred thousand more people than the one the series starts in: a listing count that merely held flat would be a market quietly thinning out relative to the county it has to house. The series opens at 16.3 per 10,000 in July 2016 and reaches 13.3 now.
Read the peaks and troughs as seasons, not as news. New listings run a hard annual sawtooth — sellers come to market in spring and go quiet in December — so the high of 21.1 in May 2018 and the low of 2.9 in December 2022 are the two ends of that cycle as much as they are the two ends of a trend. The year-on-year change is the honest comparison, and it puts June 2026 1.9% above the same month a year earlier.
This counts listings appearing, not homes selling: it is the supply side of the market, and the listing count itself is the right measure of how much work the market is doing. This one measures how much housing reaches the market relative to the size of the county. The denominator is OFM’s April 1 county estimate, interpolated between years rather than held as a step — county population between estimates genuinely moves smoothly, and a step would inject a false twelve-month sawtooth into a series that already has a real one.
Sources: Realtor.com Real Estate Data monthly inventory, King County (new listing count); Washington State Office of Financial Management April 1 county population estimates, interpolated to monthly. The rate is computed from the two series at build time rather than stored. Bench post — generated from the latest observation in the site database.
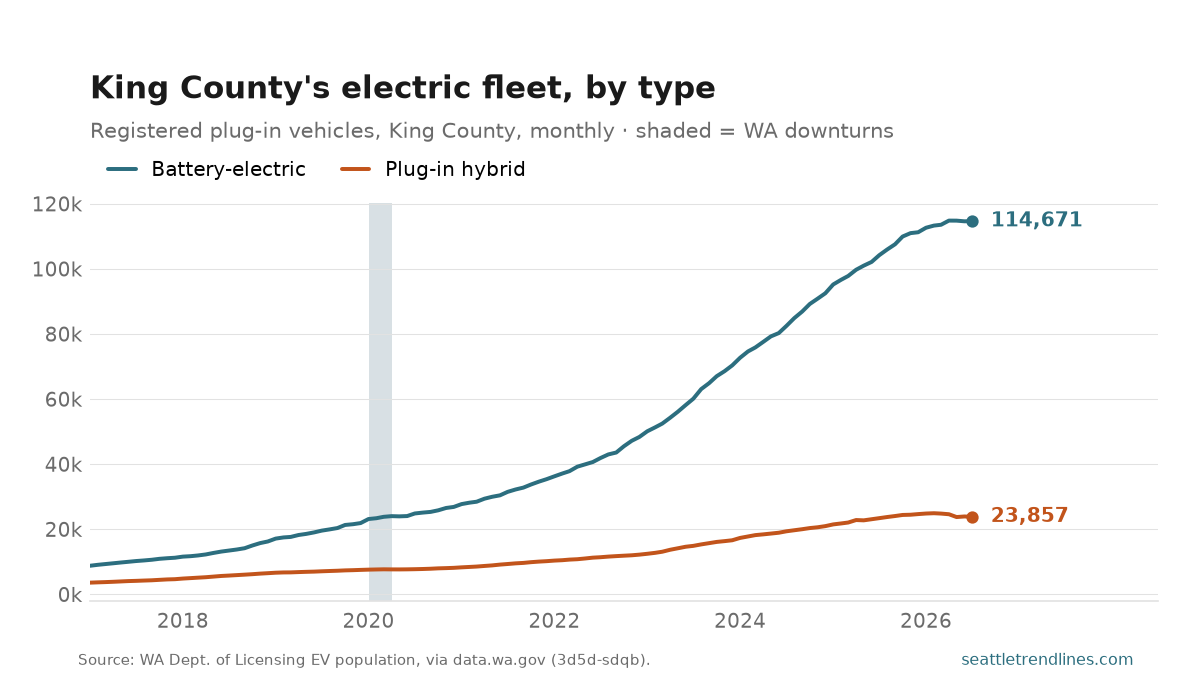
King County had 140,695 plug-in vehicles registered in July 2026. The split is the interesting part: 117,182 battery-electric cars, up 12.5% on the year, against 24,539 plug-in hybrids, up 4.1%. Battery-electrics are 83% of the fleet.
The statewide post charts the total; this is the county underneath it, and the question it answers is whether the plug-in hybrid was a transition or a destination. The two lines have very different slopes, and the gap between them has widened every year — the hybrid with a cord looks less like a step toward the battery car than like a product the battery car went around.
These are registrations in force, not sales: a stock that grows when cars are bought and shrinks when they leave the state or the road, so a month that falls is not a month nobody bought an EV. Vehicles are counted where they are registered, which is the owner’s address rather than where the car is driven.
Source: Washington State Department of Licensing, Electric Vehicle Population Size History By County, via data.wa.gov 3d5d-sdqb, King County rows, registrations in force. Auto-generated each build.
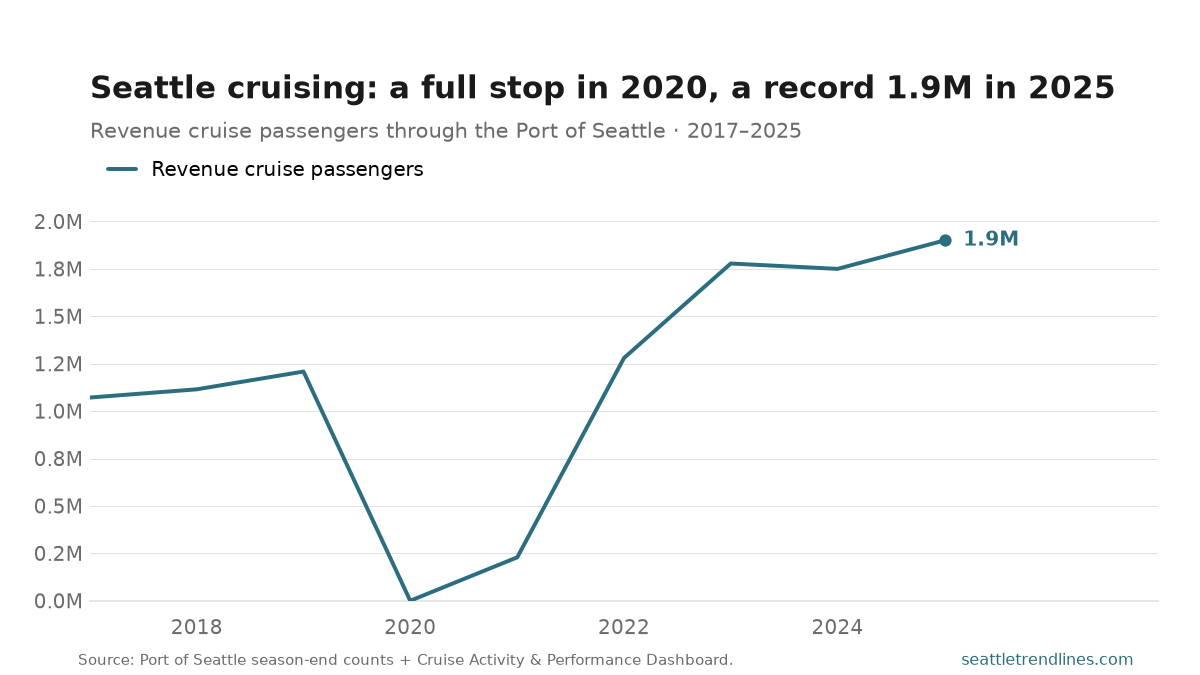
Seattle is the busiest home port for Alaska cruising in the country, and its passenger count is one of the most dramatic V’s you’ll find in any local time series. The Port crossed one million revenue passengers for the first time in 2017 and hit 1.21 million in 2019. Then, in 2020, the season simply didn’t happen — the pandemic cancelled every sailing, and the count went to zero for the first time since scheduled cruising began in 2000. A partial, delayed 2021 season carried about 229,000.
What happened next is the part worth dwelling on: the recovery wasn’t slow. By 2022 — the first normal season back — passenger volume was already at 1.28 million, above the 2019 peak. It has climbed every year since, to 1.78 million in 2023 and a record 1.9 million in 2025, roughly 57% above the pre-pandemic high. Set that against the parts of the Seattle economy still grinding back toward 2019 — downtown office occupancy, transit ridership — and the cruise terminals stand out as the rare sector that didn’t just recover but blew past its old ceiling.
Two caveats keep the number honest. “Revenue passengers” counts each traveler twice — once embarking, once disembarking — so the 1.9 million represents roughly 950,000 individual people (in 2023, 1.78 million revenue passengers were 907,572 individuals). And nearly all of it is packed into a six-month April-to-October season, which is why the working waterfront, the hotels, and Sea-Tac feel it so sharply in summer and not at all in winter. The Port pegs the annual economic impact at about $1.2 billion. From a standing start of six ships and 6,000 passengers in 1999, that’s a quarter-century climb interrupted by exactly one very bad year.
Source: Port of Seattle, season-end cruise counts and Cruise Activity & Performance Dashboard. Figures are revenue passengers (embarking + disembarking) per season; some years are the Port’s officially reported/rounded totals. 2020 = 0 (season cancelled for COVID-19). Updated each fall at season’s end.
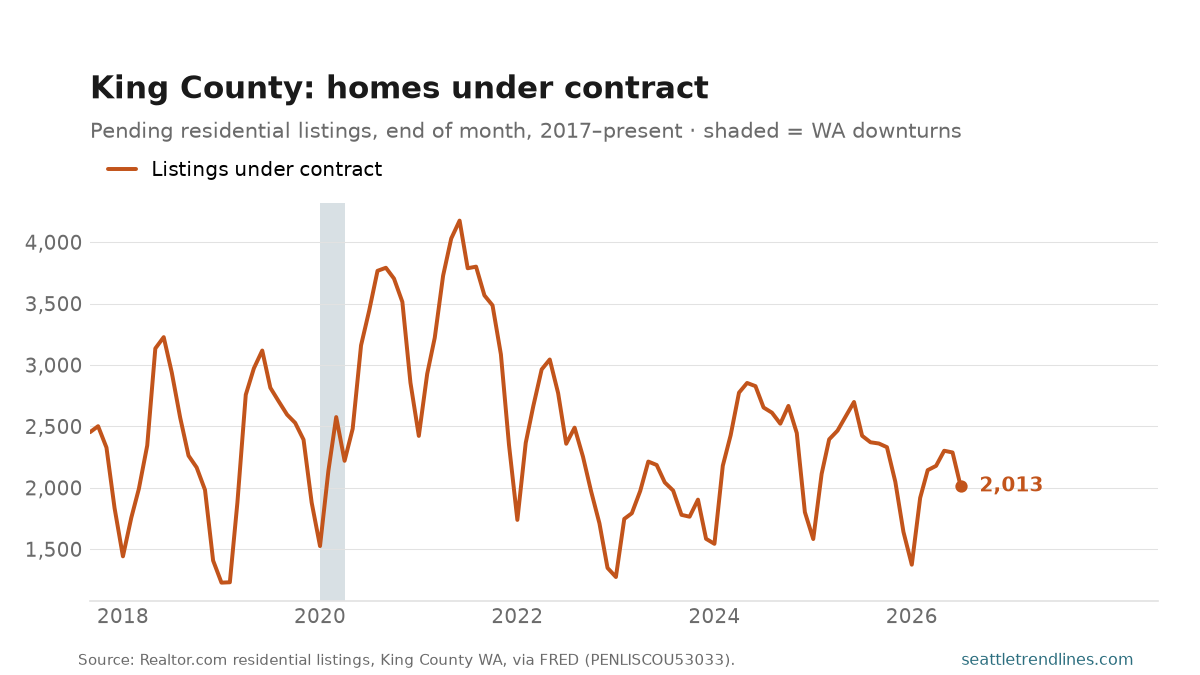
2,013 King County homes were under contract at the end of July 2026, down 17.0% from a year earlier. The count has run between 1,228 (January 2019) and 4,177 (June 2021).
Pending sales are the earliest read on demand in this data. A closed sale is a decision made thirty to forty-five days ago and a price index is slower still; a pending sale is a buyer who committed this month. It is the demand-side twin of new listings, and the two together explain the inventory number better than inventory explains itself.
It is a count of contracts, not of closings — some share falls through on financing or inspection and never becomes a sale. Seasonal, and not seasonally adjusted, so compare with the same month a year earlier.
Source: Realtor.com residential listings, King County WA (FIPS 53033), via FRED PENLISCOU53033. Auto-generated each build.
What’s coming on seattletrendlines.com the week of August 24–28 — 10 posts, two a day, every weekday.
Monday, August 24 — Seattle’s cruise business: from a 2020 shutdown to a record 1.9 million; King County homes under contract, July 2026.
Tuesday, August 25 — New listings per 10,000 King County residents, June 2026; King County’s electric fleet, July 2026.
Wednesday, August 26 — The river Seattle drinks, July 2026; What moves through the gateway, 2025.
Thursday, August 27 — What it costs to keep Seattle comfortable, 2025; City and county, 1990 to 2026.
Friday, August 28 — Seattle’s crimes against society, June 2026; Seattle building permits, July 2026.
This is the plan, not a promise. Every weekday post here is tied to a data release, and a release that slips takes its post with it — the post simply waits for the day its numbers land. A figure that arrives early, a revision worth writing about, or an unexpected story out of Seattle can just as easily add a post that isn’t on this list. Expect the week to look roughly like this, and expect at least one day of it not to.
The week of August 17–21 on seattletrendlines.com, in 9 posts.
Monday, August 17 — Seattle Fire overdose responses, July 2026. Seattle Fire was dispatched to 98 overdose calls in July 2026, down 46.7% from a year earlier. Over the life of the series the monthly count has run between 68 (August 2022) and 233 (October 2023).
Monday, August 17 — Battery or hybrid: Washington’s EV mix, July 2026. Washington had 235,196 battery-electric vehicles registered in July 2026, up 15.9% on the year, and 57,080 plug-in hybrids, up 8.3%. Pure battery cars are 80% of the state’s plug-in fleet.
Tuesday, August 18 — Seattle gas prices in real terms, July 2026. A gallon of regular cost $5.24 at the Seattle pump in July 2026. The series is deflated to the latest month, so that is also this month’s figure in today’s money; what moves is what the old prices are worth.
Tuesday, August 18 — What the Seattle metro economy is worth, 2023. Everything produced in the three-county Seattle metro came to $567 billion in 2023, up 9.8% on the year. That is 256% more than the $159 billion the same three counties produced in 2001.
Wednesday, August 19 — The crime category that isn’t one, June 2026. Seattle police filed 257 offenses under the category ANY in June 2026 — neither a crime against a person, nor against property, nor against society, which are the three NIBRS is supposed to sort every offense into.
Wednesday, August 19 — Seattle inflation against the country, June 2026. Prices in the Seattle metro were 4.5% higher than a year earlier in June 2026. Nationally the figure was 3.4% — a gap of 1.2 points, with Seattle running hotter.
Thursday, August 20 — What King County sellers put up, July 2026. King County sellers listed 2,940 homes in July 2026, up 5.4% from a year earlier. The series has run from 672 in December 2022 to 4,684 in May 2019.
Thursday, August 20 — Washington jobless claims, week of Aug 8, 2026. Washington workers filed 5,307 initial unemployment claims in the week ending Aug 8, 2026; the steadier four-week average is 4,749, down 5.9% from a year ago.
Friday, August 21 — What King County sellers are asking, July 2026. The median King County home was listed at $850,000 in July 2026, down 2.7% from a year earlier. The series high is $949,248 (May 2022); the low is $550,000 (December 2016).
The week in review: every post from August 17–21, summarised from its own listing blurb and linked. Assembled each Saturday from the posts that actually published that week.
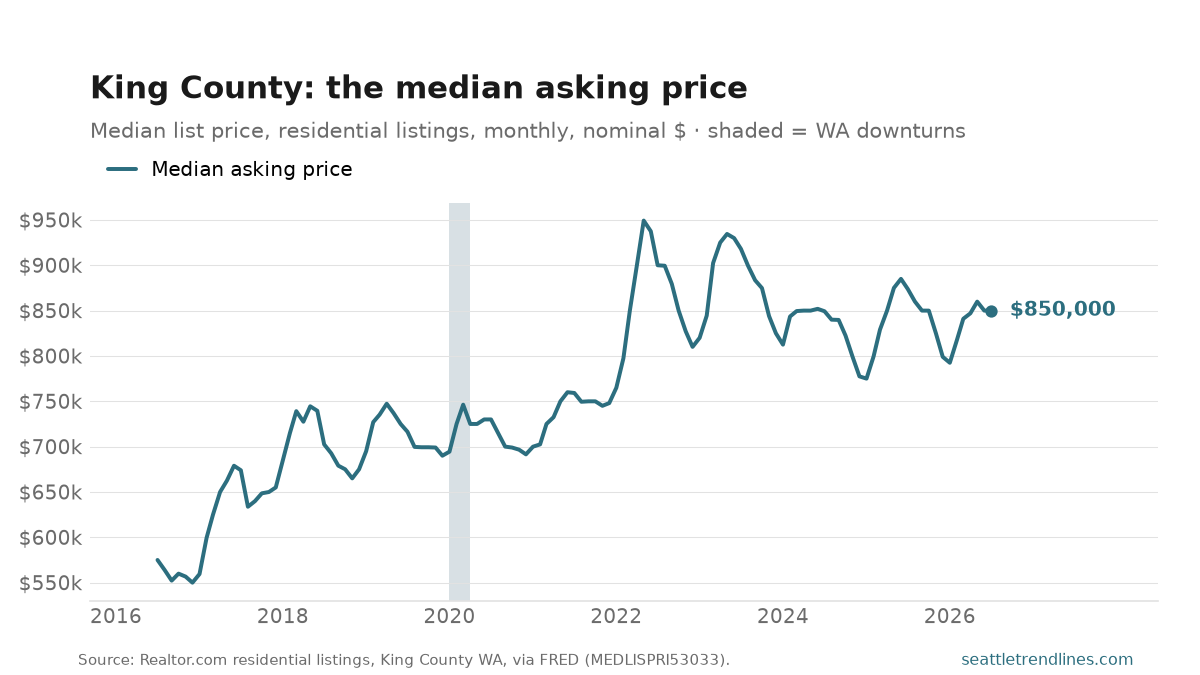
The median King County home was listed at $850,000 in July 2026, down 2.7% from a year earlier. The series high is $949,248 (May 2022); the low is $550,000 (December 2016).
This is what sellers want, which is a different and less careful number than what buyers pay. It moves with the mix of what happens to be on the market — a spring full of Eastside houses lifts it without any individual home getting more expensive — which is exactly the problem Case-Shiller is built to avoid by tracking repeat sales of the same properties. Read this one for the asking mood and that one for the price level.
What it has going for it is speed: an asking price exists the day the sign goes up, while Case-Shiller is a three-month average published two months late. Nominal dollars, not seasonally adjusted.
Source: Realtor.com residential listings, King County WA (FIPS 53033), via FRED MEDLISPRI53033. Nominal dollars. Auto-generated each build.