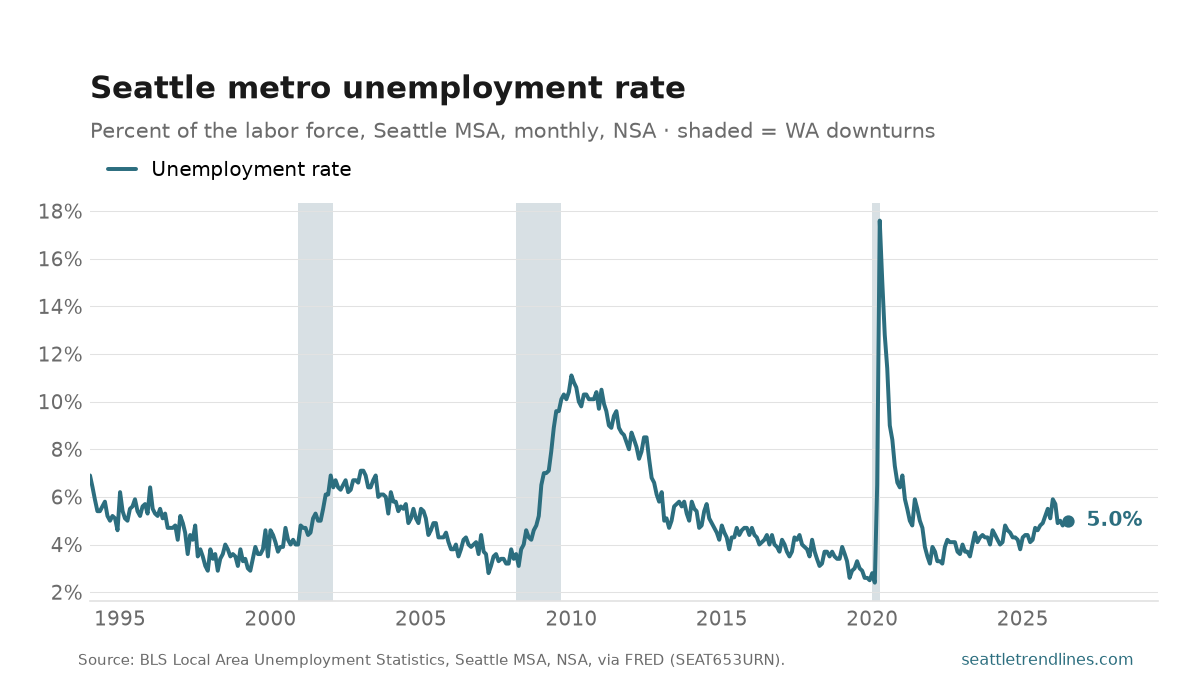
Seattle-metro unemployment was 5.0% in July 2026, the newest month in the series and the monthly update to the unemployment post. That is up 0.4 points from 4.6% in the same month a year earlier, and unchanged the month before. The chart carries the full history back to 1994; the older post’s version of it stops at the month it was published with, so the two lines end in different places on purpose.
The year-ago comparison is the one to trust here. These numbers are not seasonally adjusted, so part of every month-to-month move is just the calendar — hiring for the holidays, students leaving and re-entering the labor force — and only the same month a year earlier strips that out. Keep the scale in mind too: this series ran from 2.4% in February 2020 to 17.6% in April 2020, so a few tenths of a point is a wobble, not a turn. And because the rate is a ratio, it can fall for the wrong reason — people who stop looking for work leave the denominator, and the rate improves with nobody hired.
Source: U.S. Bureau of Labor Statistics, Local Area Unemployment Statistics, Seattle–Tacoma–Bellevue MSA unemployment rate, not seasonally adjusted, via FRED SEAT653URN. Auto-generated each build.
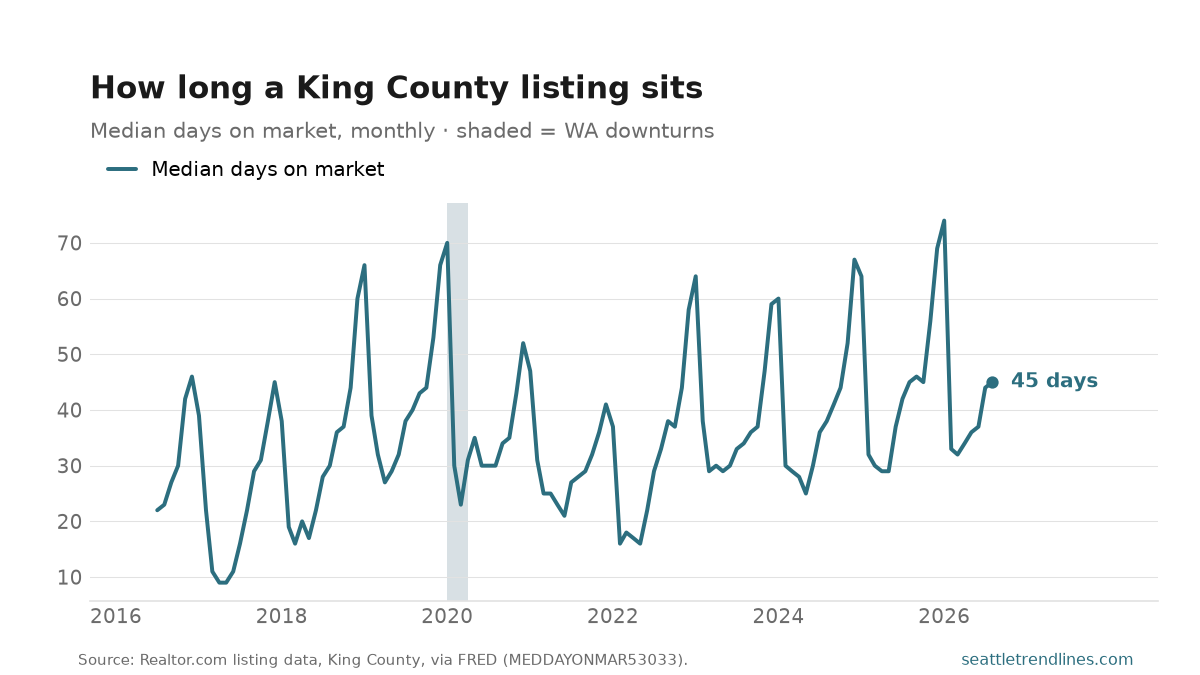
The median King County listing sat 45 days on the market in August 2026, against 45 days a year earlier. Days on market is the market’s pulse rather than its price: it says how long sellers wait, and it moves before asking prices do, because a seller cuts the price only after the waiting has already happened.
The seasonal pattern is severe and it is not a trend — listings move fastest in spring and slowest in December, every year, and the only honest comparison is to the same month a year ago. Over the whole series the fastest month was 9 days (April 2017) and the slowest 74 (January 2026).
Source: Realtor.com median days on market, King County WA, via FRED MEDDAYONMAR53033. Auto-generated each build.
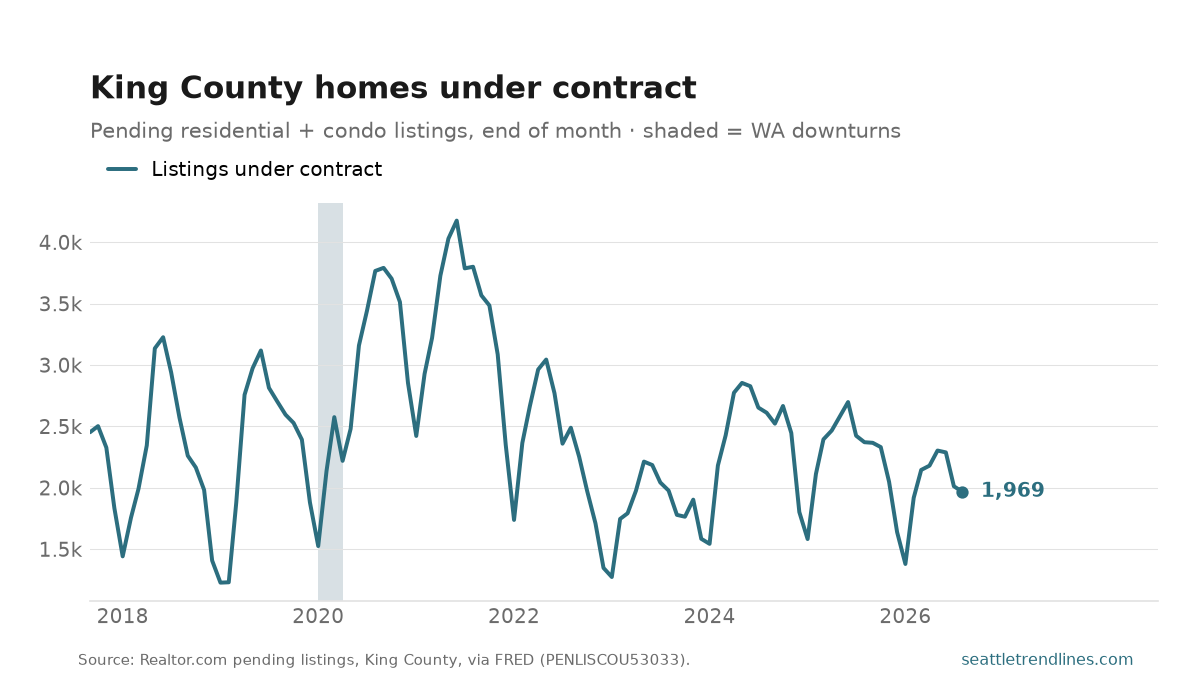
1,969 King County listings were under contract at the end of August 2026, down 17.0% from a year earlier. Pending sales are the closest thing this site carries to a leading indicator of the housing market: a deal goes pending weeks before it closes, so this line turns before recorded sale prices do.
It is also the demand side of the same monthly Realtor.com drop that gives us inventory and asking prices. Inventory rising while pendings fall is a market cooling; both rising together is just a busy spring.
Source: Realtor.com pending residential listings, King County WA, via FRED PENLISCOU53033. Auto-generated each build.
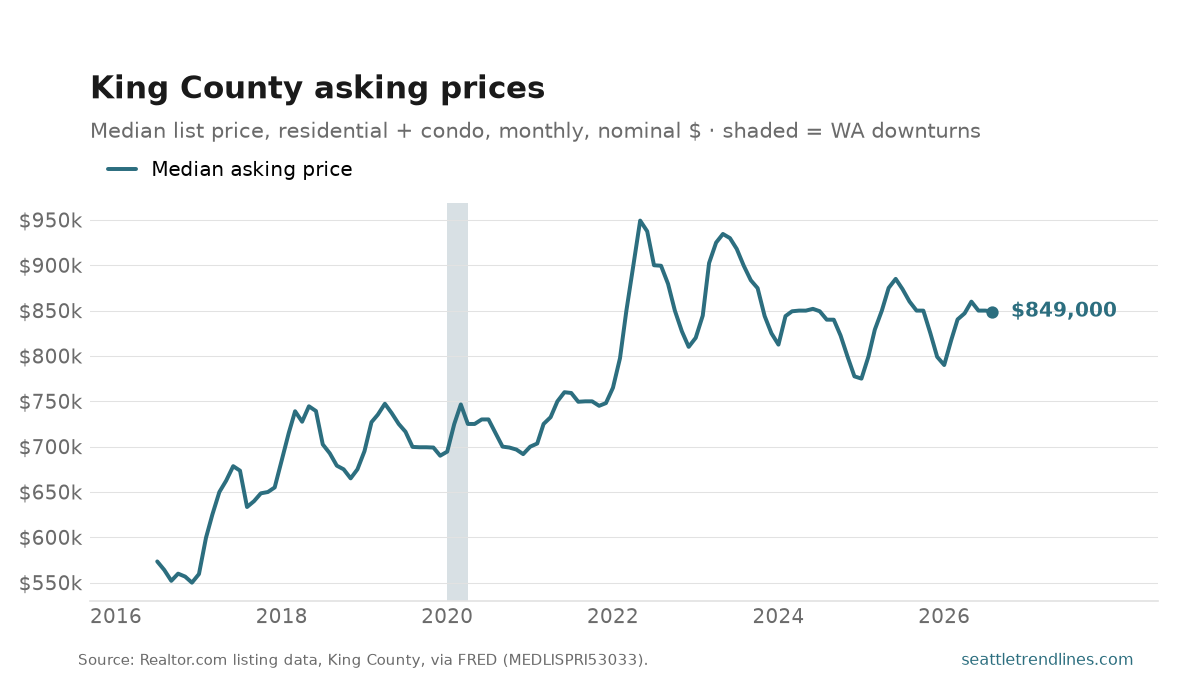
The median King County listing asked $849,000 in August 2026, down 1.3% from a year earlier. Read this as what sellers want, not what buyers pay: it is the midpoint of what is on the market, so it moves with the mix of homes listed as much as with prices. A month heavy on Eastside houses lifts it without anything getting more expensive.
For the price of what actually changes hands, home values is the better series — it holds the mix constant. This one is the faster read, and it is the one sellers are looking at.
Source: Realtor.com median listing price, King County WA, via FRED MEDLISPRI53033, nominal dollars. Auto-generated each build.
What’s coming on seattletrendlines.com the week of September 7–11 — 10 posts, two a day, every weekday.
Monday, September 7 — King County asking prices, August 2026; King County homes under contract, August 2026.
Tuesday, September 8 — How long a King County listing sits, August 2026; Seattle-metro unemployment, July 2026.
Wednesday, September 9 — Seattle’s labor force, July 2026; Link light rail ridership, July 2026.
Thursday, September 10 — King County Metro bus ridership, July 2026; Seattle’s air, April 2026 (pending — its numbers haven’t landed yet).
Friday, September 11 — Seattle offences against persons, July 2026; Seattle offences against property, July 2026.
This is the plan, not a promise. Every weekday post here is tied to a data release, and a release that slips takes its post with it — the post simply waits for the day its numbers land. A figure that arrives early, a revision worth writing about, or an unexpected story out of Seattle can just as easily add a post that isn’t on this list. Expect the week to look roughly like this, and expect at least one day of it not to.
The week of August 31 – September 4 on seattletrendlines.com, in 9 posts.
Monday, August 31 — Thirty years of Seattle school spending, to 2022. Seattle Public Schools spent $23,519 per pupil in 2022, in constant dollars — down 2.1% on the year, and 72% above the series low of $13,702 in 1995. The real peak was $24,313 in 2020.
Tuesday, September 1 — King County’s share of Washington’s EVs, July 2026. 48.5% of Washington’s electric vehicles were registered in King County in July 2026 — 140,695 of the state’s 291,146. The share was 57.0% at its height, in February 2017.
Tuesday, September 1 — Seattle building permits, July 2026. On a trailing 12-month basis, the Seattle metro permitted 20,712 housing units through July 2026, up 35.8% from a year earlier. This updates the permit slump; the 12-month sum smooths the monthly noise so the trend is the signal.
Wednesday, September 2 — What share of Seattle works where, July 2026. Information employers were 6.2% of all Seattle-metro payrolls in July 2026; manufacturers were 7.8%. In 1990 manufacturing was 18% and nothing else came close.
Wednesday, September 2 — Battery or plug-in hybrid, July 2026. Washington registered 235,196 battery-electric vehicles and 57,080 plug-in hybrids in July 2026. Batteries are 80% of the state’s electric fleet, and their count is up 15.9% on the year.
Thursday, September 3 — Sea-Tac against normal, August 2026. August 2026 at Sea-Tac ran 0.9°F above normal. Normal here is the 1991-2020 average for that same month, which is the standard climate baseline — so this is a comparison with the recent past, not with the start of the record.
Thursday, September 3 — Construction’s share of Seattle jobs, July 2026. Construction and mining was 5.7% of Seattle-metro payroll jobs in July 2026 — 124,000 jobs. The share peaked at 7.5% in August 2007 and bottomed at 4.5% in January 2012.
Friday, September 4 — King County for-sale inventory, August 2026. King County ended August 2026 with 7,366 active for-sale listings, up 27.4% from a year earlier — the monthly update to King County’s inventory rebuild.
Friday, September 4 — What King County sellers listed, August 2026. King County sellers put 2,512 new listings on the market in August 2026, up 12.3% from the same month a year earlier.
The week in review: every post from August 31 – September 4, summarised from its own listing blurb and linked. Assembled each Saturday from the posts that actually published that week.
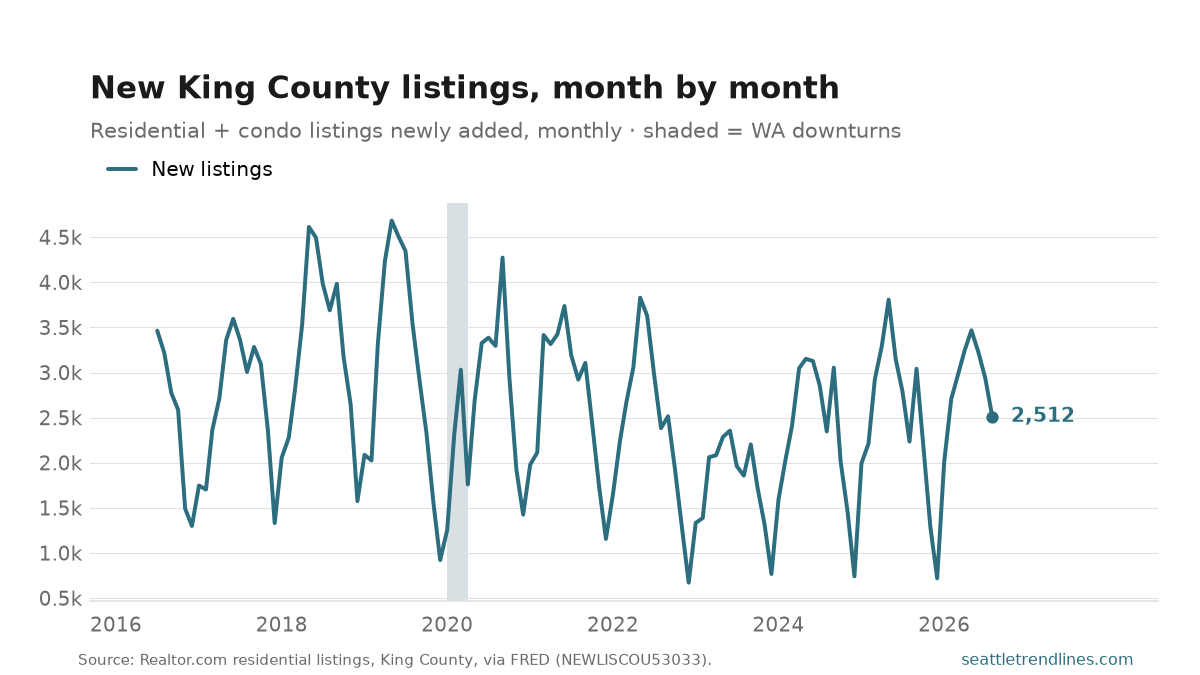
King County sellers put 2,512 new listings on the market in August 2026, up 12.3% from the same month a year earlier. The year-over-year comparison is the only fair one here: this series has a spring peak and a December trough every single year, so a fall from June to November says nothing except that it got dark.
New listings are the supply side of the inventory number — what sellers add, rather than what is sitting unsold. The two move apart when demand shifts: inventory can climb on flat new listings if buyers stop absorbing them.
Source: Realtor.com new residential listings, King County WA, via FRED NEWLISCOU53033. Auto-generated each build.
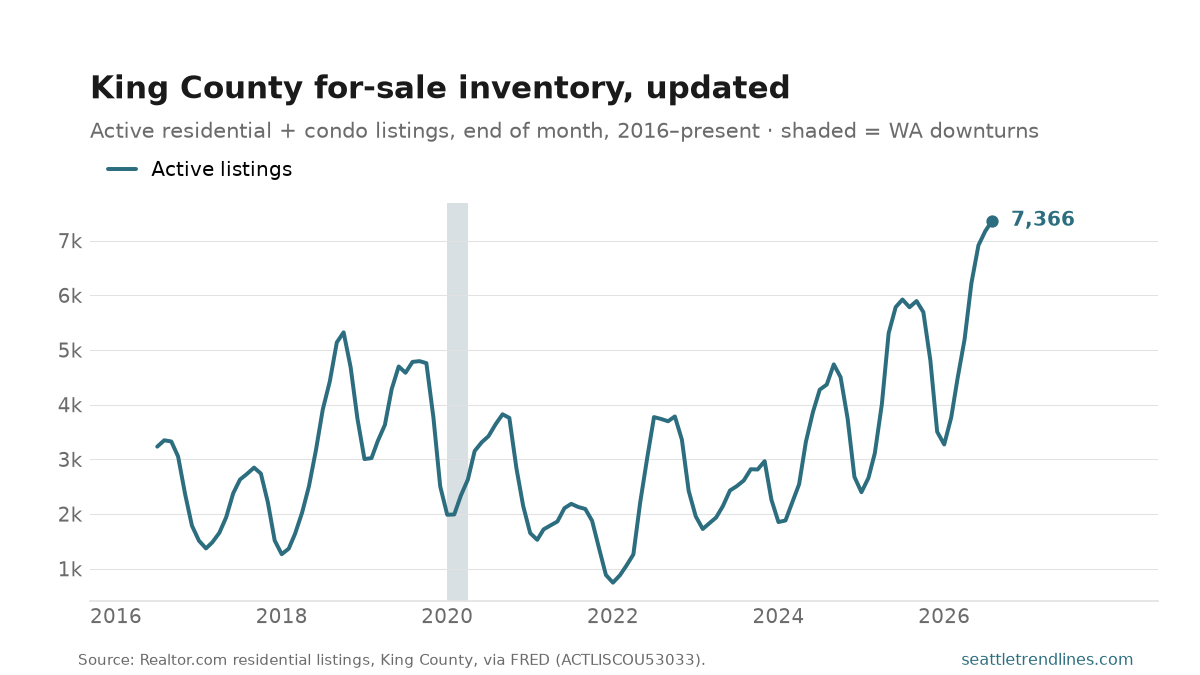
King County ended August 2026 with 7,366 active for-sale listings, up 27.4% from a year earlier — the monthly update to King County’s inventory rebuild.
Source: Realtor.com residential listing inventory, King County WA, via FRED ACTLISCOU53033. Auto-generated each build.
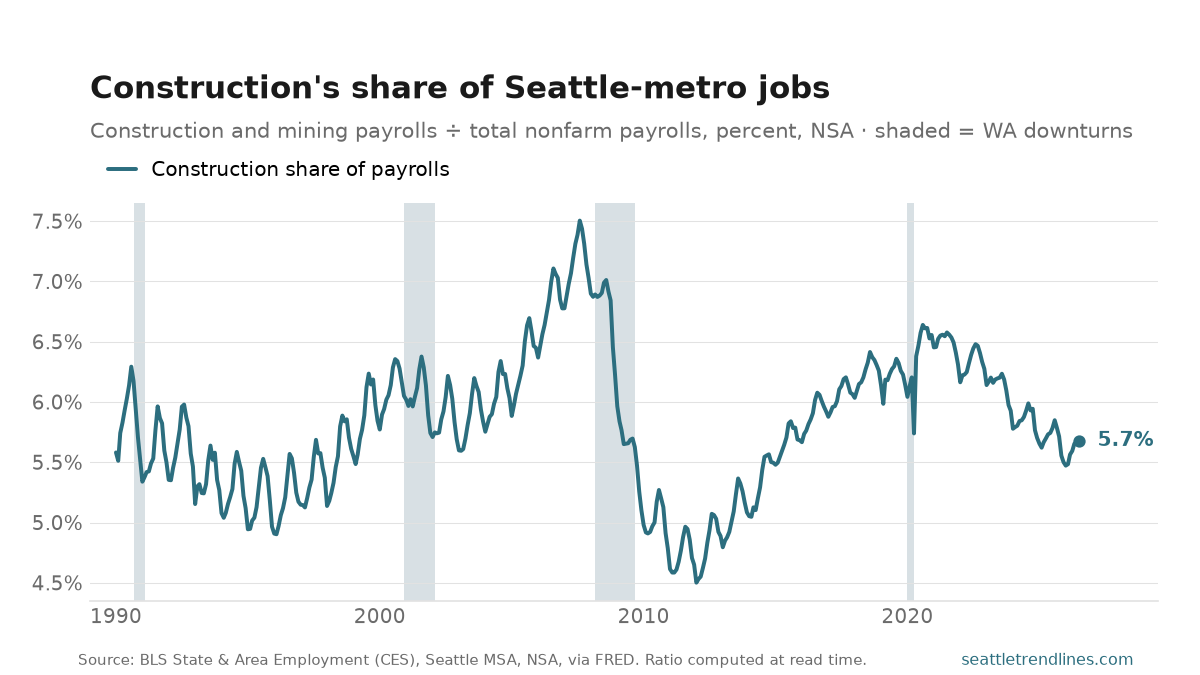
Construction and mining was 5.7% of Seattle-metro payroll jobs in July 2026 — 124,000 jobs. The share peaked at 7.5% in August 2007 and bottomed at 4.5% in January 2012.
This is the closest thing the site has to a building-cycle indicator that is not about permits. It measures how much of the region’s labour is pointed at construction, and unlike the job count it cannot be flattered by an economy that is simply larger than it used to be — the share fell by nearly a third after 2007 while the metro kept adding jobs everywhere else.
Numerator and denominator are the same BLS release for the same metro, so the share stays consistent through revisions, and it is computed at read time rather than stored. Not seasonally adjusted: construction has a real summer, so compare to the same month a year earlier.
Source: U.S. Bureau of Labor Statistics, State & Area Employment, mining, logging and construction against total nonfarm payrolls, Seattle–Tacoma–Bellevue MSA, not seasonally adjusted, via FRED. The share is derived at read time. Auto-generated each build.
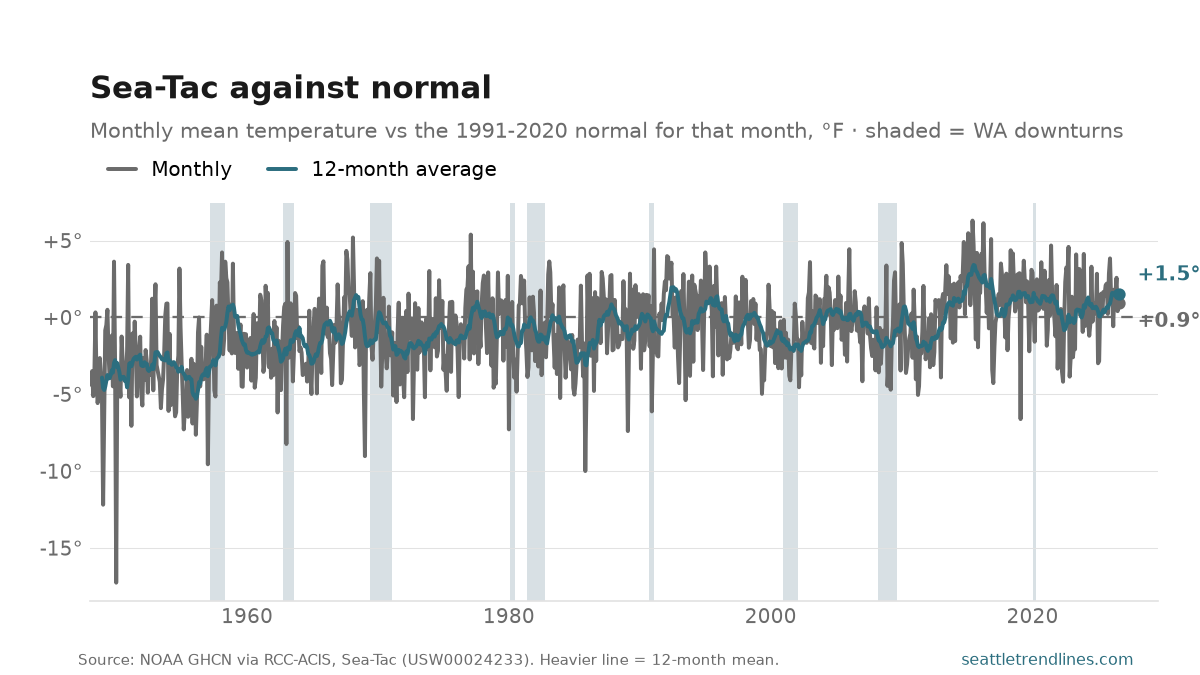
August 2026 at Sea-Tac ran 0.9°F above normal. Normal here is the 1991-2020 average for that same month, which is the standard climate baseline — so this is a comparison with the recent past, not with the start of the record.
Across the whole series, August has averaged -1.1°F against that baseline, over 79 years. The warmest was +4.3 (1967) and the coldest -6.2 (1954). A single month is weather; the reason to post one every month is that the band they fall in has moved — which is what the 12-month average on the chart is there to show.
The station is the caveat, and it is a real one. Sea-Tac is the only continuous daily record in this region back to 1948, and it is an airport twelve miles south of downtown with far more tarmac around the thermometer than it had then. Some of the drift in this line is the airport growing, not the climate — that is why the anomaly is measured against a fixed 1991-2020 baseline rather than against the 1950s, which would read the pavement as warming. It is still the best record there is.
Source: NOAA Global Historical Climatology Network daily records for Seattle-Tacoma International Airport (USW00024233), via RCC-ACIS, aggregated to monthly means and differenced against the 1991-2020 normal for each calendar month. Auto-generated each build.