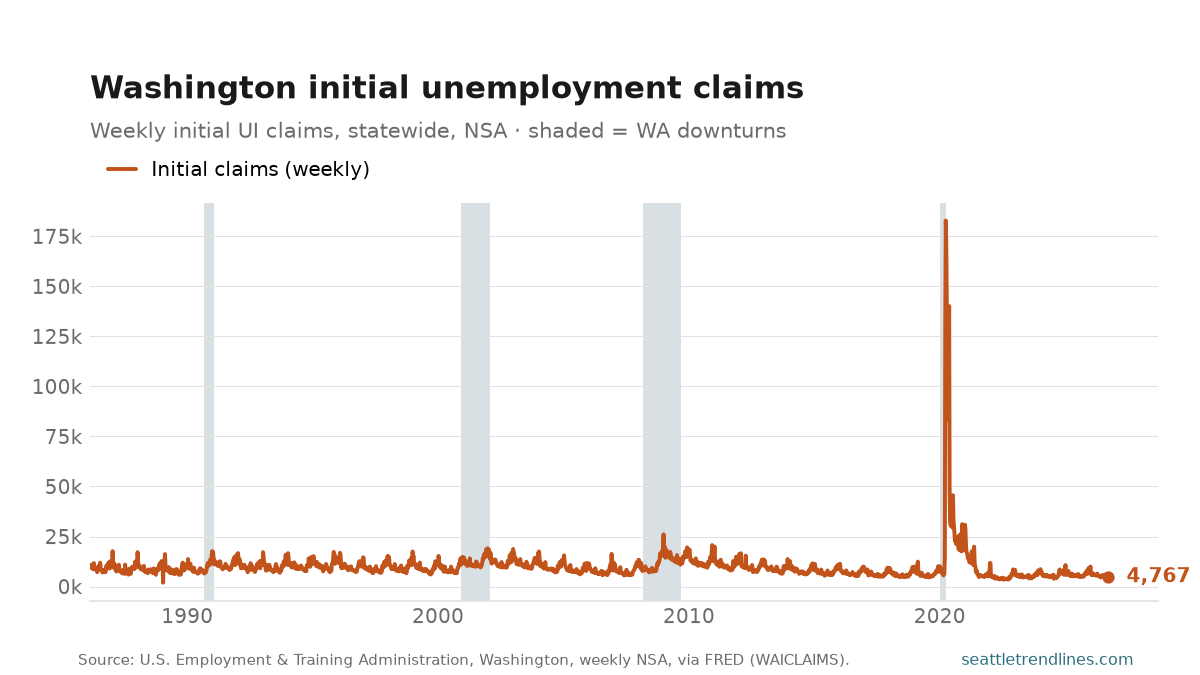
Washington workers filed 4,767 initial unemployment claims in the week ending Sep 12, 2026; the steadier four-week average is 4,735, down 8.0% from a year ago. Statewide, weekly, not seasonally adjusted — the update to the jobless-claims post.
Source: U.S. Employment and Training Administration, initial unemployment-insurance claims for Washington, weekly, not seasonally adjusted, via FRED WAICLAIMS. Auto-generated each build.
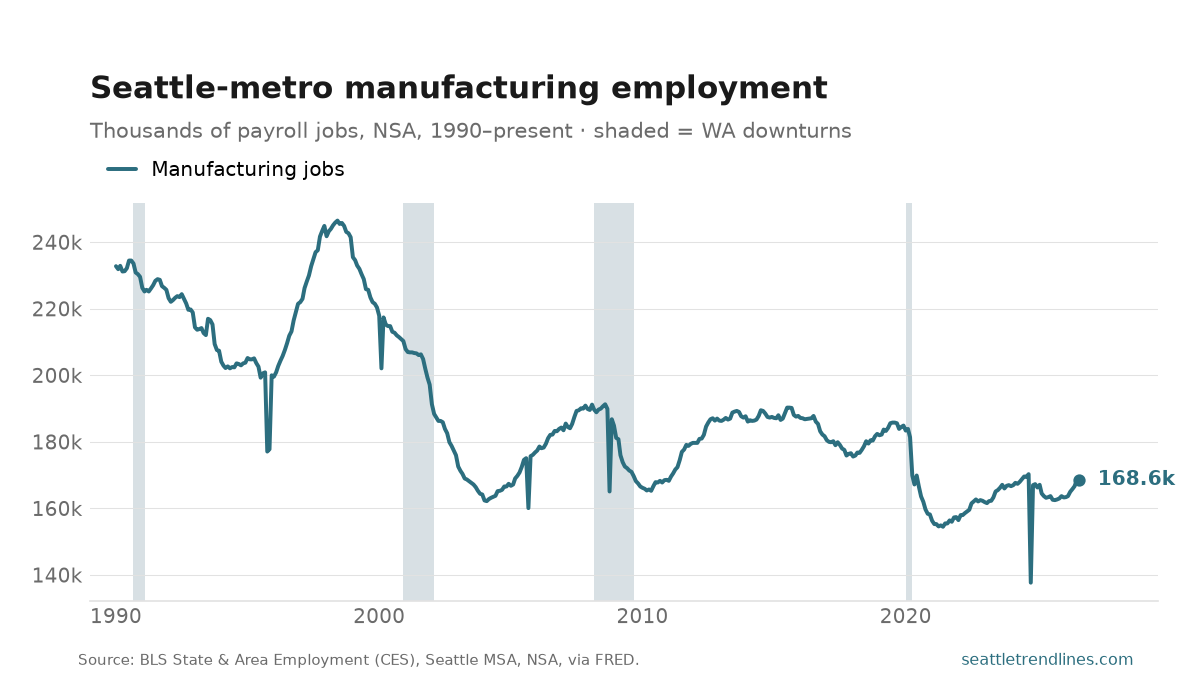
Seattle-metro manufacturers employed 168,600 people in August 2026, up 3.7% from a year earlier. The sector peaked at 246,500 jobs in June 1998 and has shed roughly 32% of that since.
In this region manufacturing is very close to a Boeing series with a rounding error attached, which is why the deep single-month notches line up with machinist strikes rather than with recessions — the data is not seasonally adjusted, so a walkout shows up whole. Reading them as anything else is the standard mistake with this chart.
The sector’s shrinking share of total payrolls is the same story told against the size of the economy, and it is the more damning version.
Source: U.S. Bureau of Labor Statistics, State & Area Employment, manufacturing, Seattle–Tacoma–Bellevue MSA, not seasonally adjusted, via FRED. Auto-generated each build.
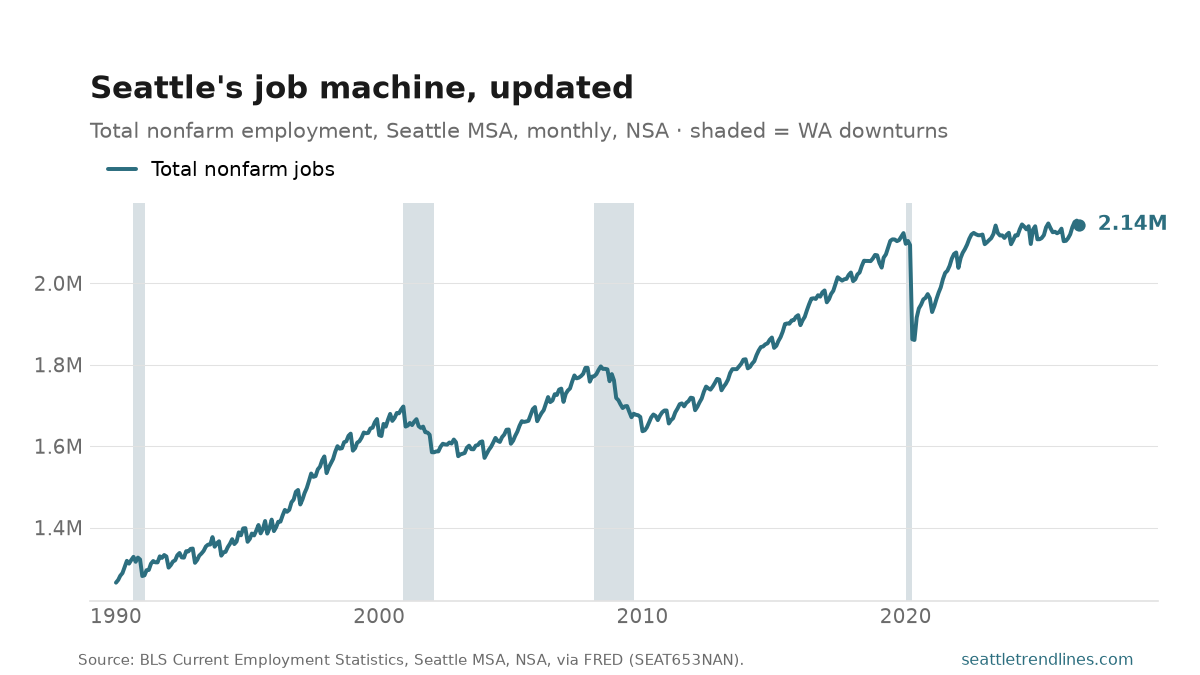
Seattle–Tacoma–Bellevue employers reported 2,143,900 nonfarm jobs in August 2026 (not seasonally adjusted), up 18,600 — +0.9% — from a year earlier. This is the monthly refresh of the stalled job machine; because the series isn’t seasonally adjusted, the year-over-year change is the one to watch.
Source: U.S. Bureau of Labor Statistics, Current Employment Statistics, Seattle–Tacoma–Bellevue MSA, not seasonally adjusted, via FRED SEAT653NAN. Auto-generated each build from the latest observation.
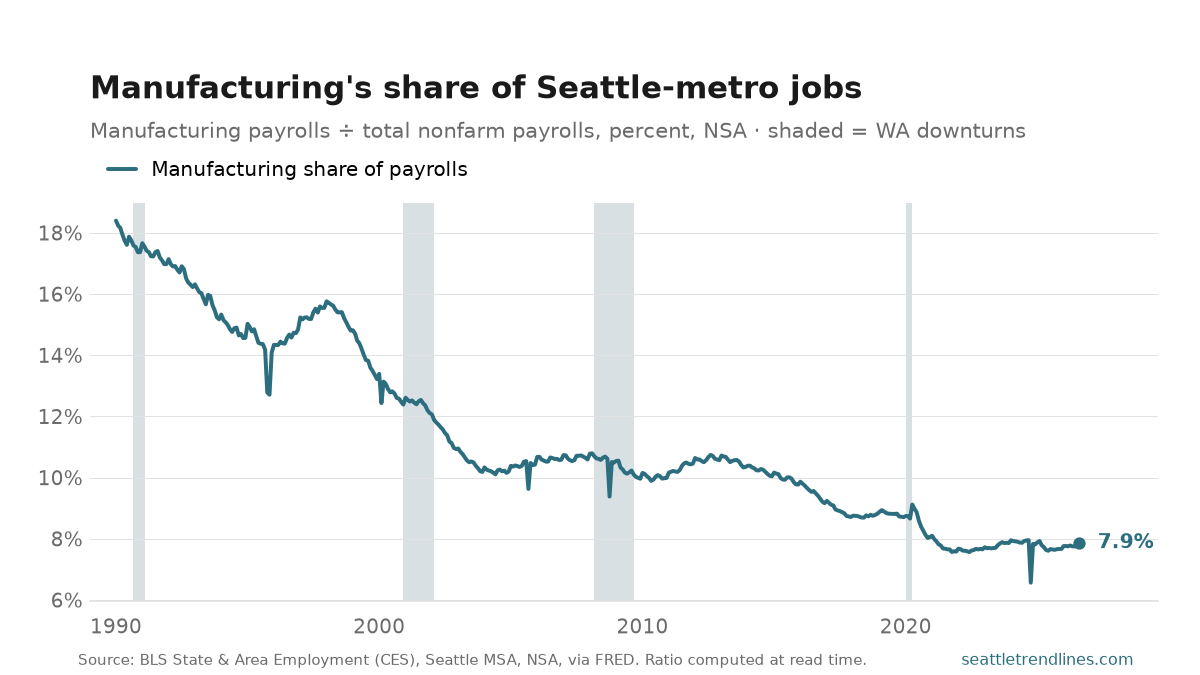
Manufacturing was 7.9% of Seattle-metro payroll jobs in August 2026: 168,600 manufacturing jobs against every payroll in the metro. The share peaked at 18.4% in January 1990.
The share falls faster than the job count does, and the difference between the two charts is the point of this one. Manufacturing employment has declined; the rest of the metro’s economy has grown. Both together are why a sector that once shaped the region’s politics now moves its headline employment number hardly at all.
Numerator and denominator come from the same BLS release for the same metro, so the share stays internally consistent even in a month the levels are revised — this is a ratio computed at read time from two stored series, never a stored series of its own.
Source: U.S. Bureau of Labor Statistics, State & Area Employment, manufacturing and total nonfarm payrolls, Seattle–Tacoma–Bellevue MSA, not seasonally adjusted, via FRED. The share is derived at read time from the two stored series. Auto-generated each build.
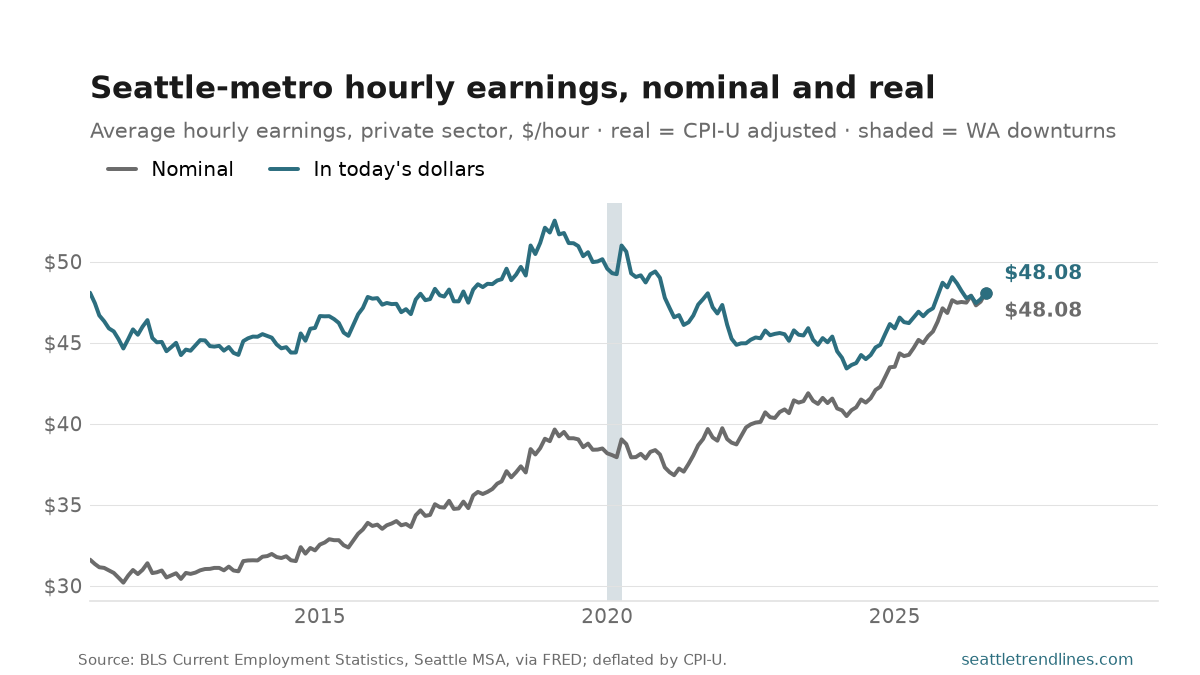
Private-sector workers in the Seattle metro averaged $48.08 an hour in August 2026. Adjusted for inflation that is $48.08 in today’s money, up 2.4% from a year earlier.
The two lines are the post. Nominal pay in this region has gone up almost every month for fifteen years, which is the number that gets announced; whether it bought more is a different question, and between 2021 and 2023 the answer was no. The real series peaked at $52.53 in February 2019.
An average, not a median, so it is pulled upward by high earners — this is a metro where that matters more than most. It also moves with who is working: a month that sheds low-wage jobs raises the average without raising anyone’s pay, which is much of what happened in 2020.
Source: U.S. Bureau of Labor Statistics, Current Employment Statistics, average hourly earnings of all private employees, Seattle–Tacoma–Bellevue MSA, via FRED; real series deflated by CPI-U to the latest available period. Auto-generated each build.
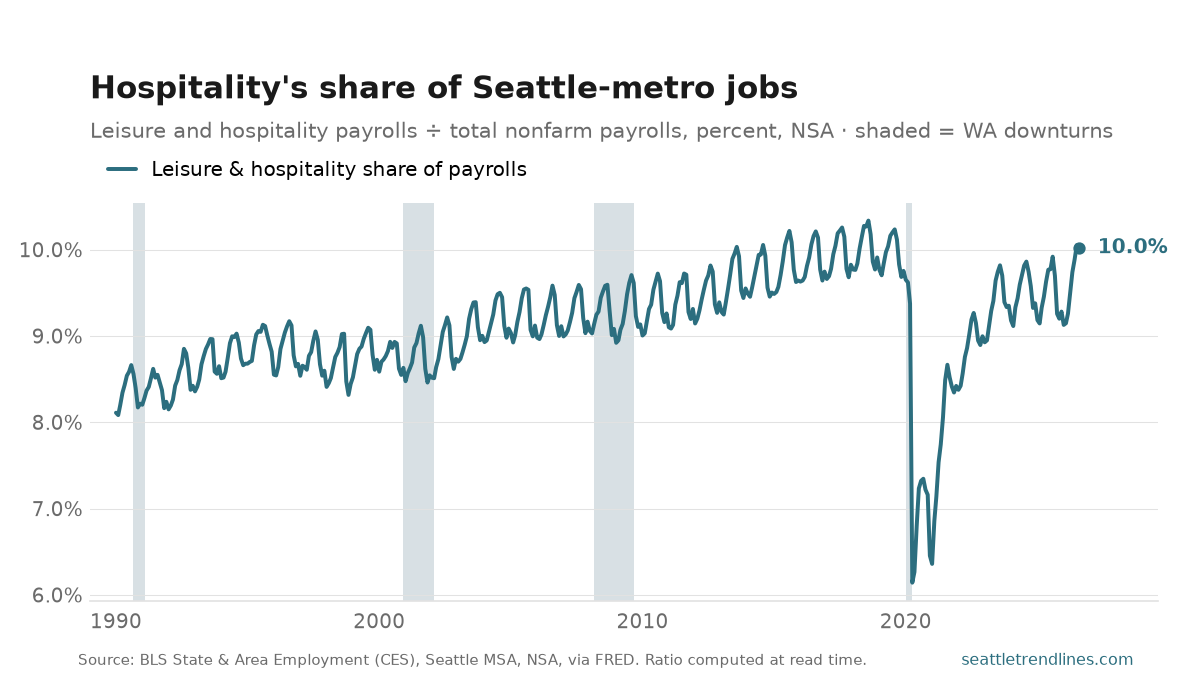
Leisure and hospitality was 10.0% of Seattle-metro payroll jobs in August 2026 — 214,800 jobs in restaurants, bars, hotels and venues.
Read this chart against manufacturing’s, because they are the same story from opposite ends. As the share of the region’s work done in factories fell, the share done serving people rose — from 8.1% when the series opens in January 1990 to a peak of 10.3% in August 2018. That is a real change in what a Seattle job is, and it is not a neutral one: these are the jobs least likely to cover what the rent takes.
The 2020 notch is the sharpest event in any series on this site — the share fell to 6.1% in April 2020, because this is the sector that could not be done from home. Same-release numerator and denominator, computed at read time, not seasonally adjusted.
Source: U.S. Bureau of Labor Statistics, State & Area Employment, leisure and hospitality against total nonfarm payrolls, Seattle–Tacoma–Bellevue MSA, not seasonally adjusted, via FRED. The share is derived at read time. Auto-generated each build.
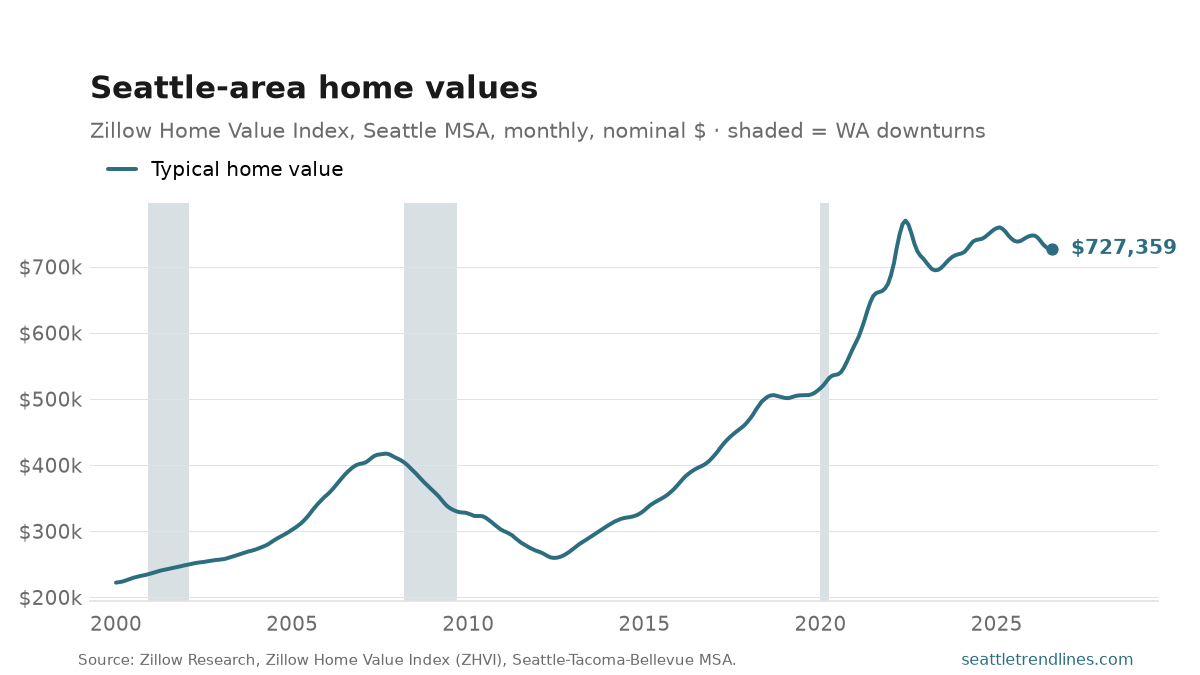
The typical Seattle-metro home was worth $727,359 in August 2026, down 1.5% from a year earlier. Against the series high of $769,953 in June 2022, that leaves the market 5.5% below its high-water mark.
ZHVI measures the value of the typical home rather than the price of the homes that happened to sell, so it does not lurch when an expensive neighbourhood has a busy month — which is exactly what makes it readable month to month, and what makes it a better trend line than asking prices.
Nominal dollars, metro-wide. Zillow revises the back series when its model is updated, so older points can move slightly between builds.
Source: Zillow Research, Zillow Home Value Index (ZHVI), all homes, Seattle–Tacoma–Bellevue MSA, nominal dollars. Auto-generated each build.
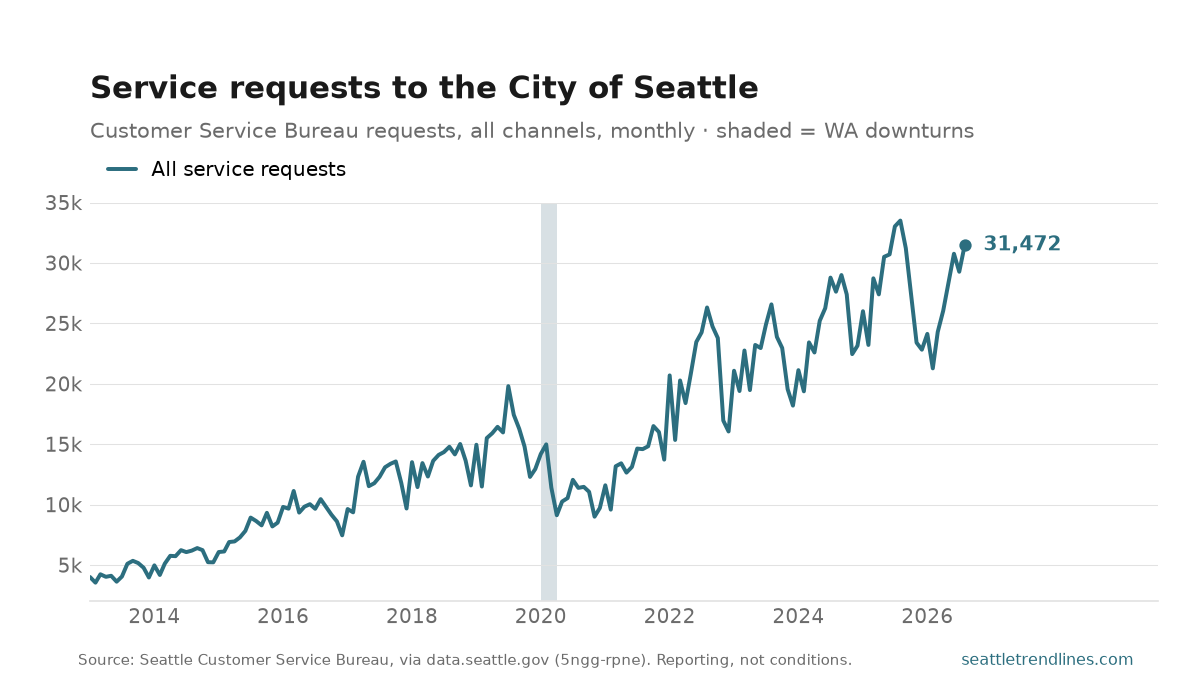
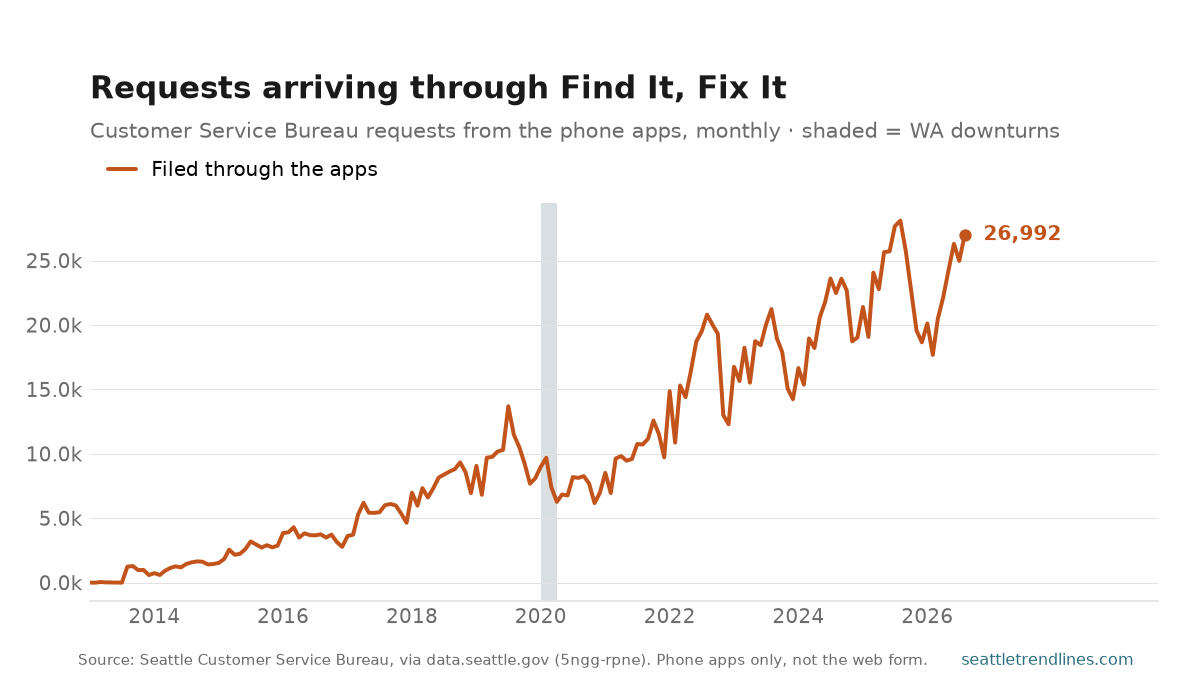
Seattle residents filed 31,472 service requests in August 2026 — potholes, graffiti, illegal dumping, abandoned vehicles, encampments — down 6.1% from a year earlier. 26,992 of them, 86%, came through the Find It, Fix It apps.
This measures reporting, not conditions, and the two come apart. A month with more graffiti reports is a month more people told the city about graffiti, which moves with how easy reporting is at least as much as with how much graffiti there is. The app split beneath the total is the evidence: intake was almost entirely phone calls when this series starts and is overwhelmingly app-based now, and a channel that takes thirty seconds collects complaints a channel that takes ten minutes never heard. Read a rise here as demand for city services being expressed, not as the city getting worse.
The independent check on any of this is a feed nobody chooses to file into — the fire department’s 911 dispatches, which are also on this site. Where the two move together, something real is happening; where only this one moves, the channel changed. Requests are dated by when they were created, and one incident reported by three neighbours is three rows.
Source: Seattle Customer Service Bureau, Customer Service Requests, via data.seattle.gov (Socrata 5ngg-rpne). The app series counts the Find It, Fix It phone apps only, not the browser intake form. Auto-generated each build.
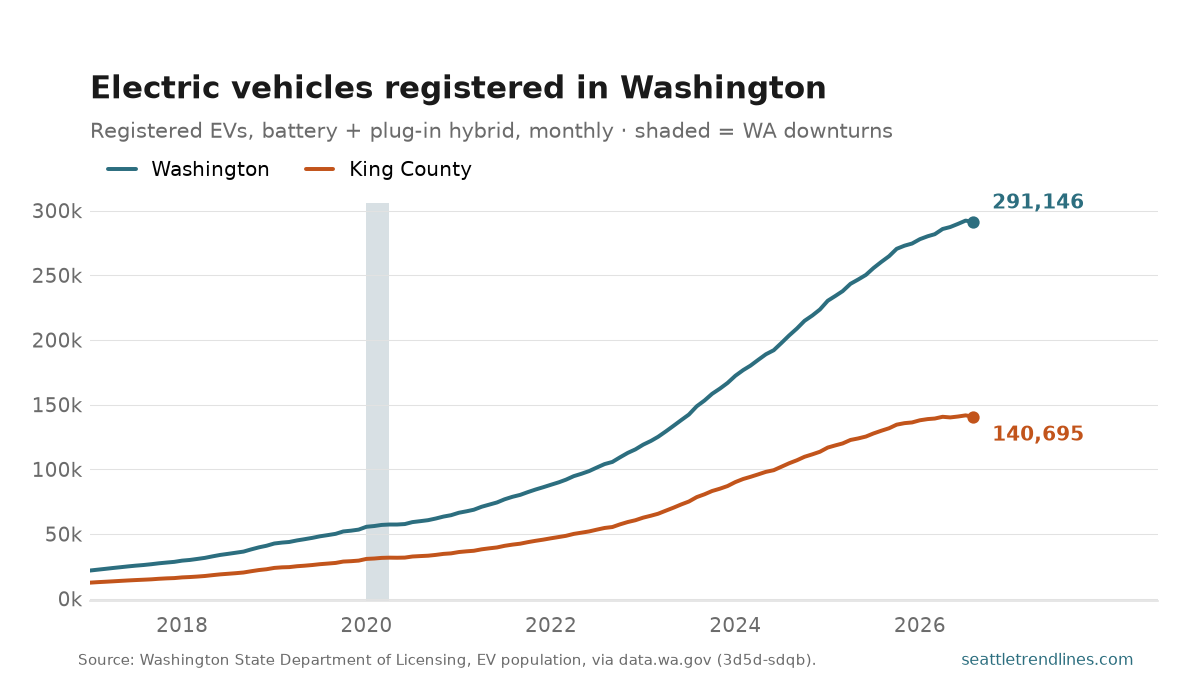
291,146 electric vehicles were registered in Washington in August 2026, up 11.8% from a year earlier. King County holds 140,695 of them — 48% of the state’s fleet, in a county with about a third of its people.
This is a stock, not sales: it counts the EVs registered and on the road in that month, so it falls only when cars leave the fleet faster than they join it. That makes the slope, rather than the level, the thing to read — a flattening line means adoption slowing, not the fleet shrinking.
Battery-electric and plug-in hybrid vehicles are both counted here; the mix between them is its own post, and the two have not grown at the same rate.
Source: Washington State Department of Licensing, Electric Vehicle Population, via data.wa.gov (Socrata 3d5d-sdqb). Counts vehicles registered in the month, not sales. Auto-generated each build.
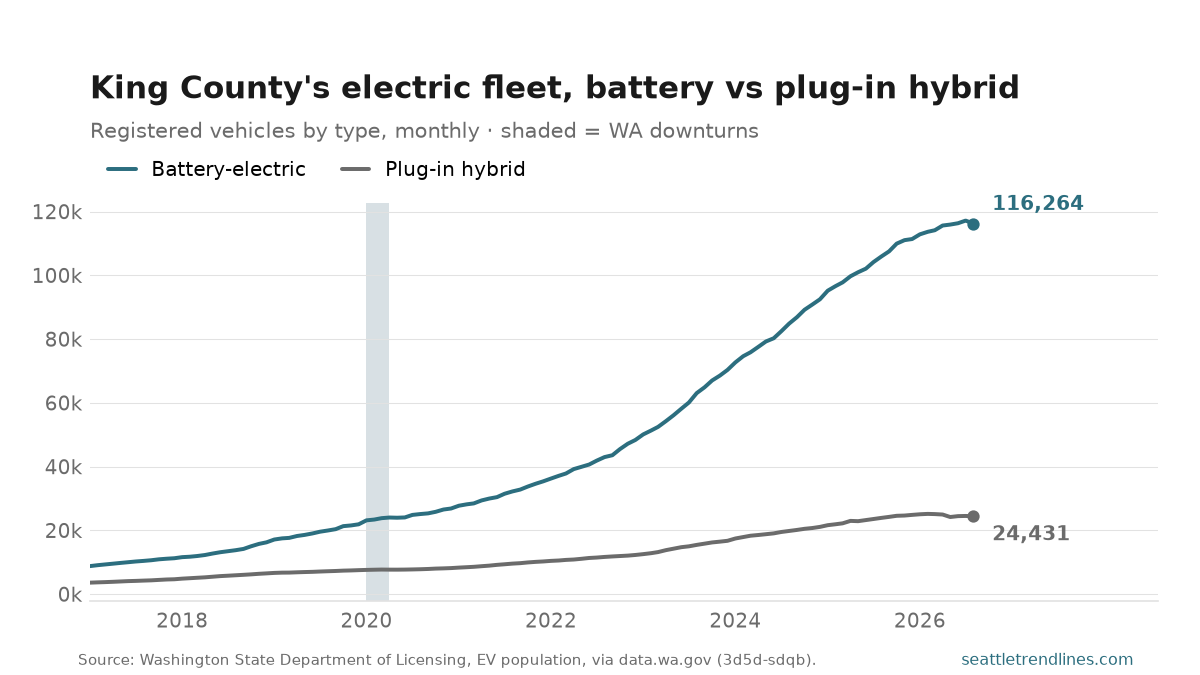
King County had 116,264 battery-electric vehicles and 24,431 plug-in hybrids registered in August 2026 — batteries are 83% of the county’s electric fleet. The battery count is up 9.8% from a year earlier.
The split is the interesting part. Plug-in hybrids were the hedge — battery for the commute, petrol for the mountain pass — and the two lines started the series close together. They are not close now, which is a statement about how far charging infrastructure and range have come rather than about policy.
Registrations are a stock, not sales: this is what was on the road that month.
Source: Washington State Department of Licensing, Electric Vehicle Population, King County, via data.wa.gov (Socrata 3d5d-sdqb). Auto-generated each build.